The three main types of reverse mortgage loans are:
FHA-insured Home Equity Conversion Mortgages, commonly called HECMs Proprietary reverse mortgages offered by private lenders Single-purpose reverse mortgages offered by some government agencies or nonprofit organizations HECMs are the most common type and the only reverse mortgages insured by the federal government. Proprietary loans are private products that may be designed for homeowners with higher-value properties. Single-purpose loans are generally limited to a specific approved expense, such as property taxes or home repairs.
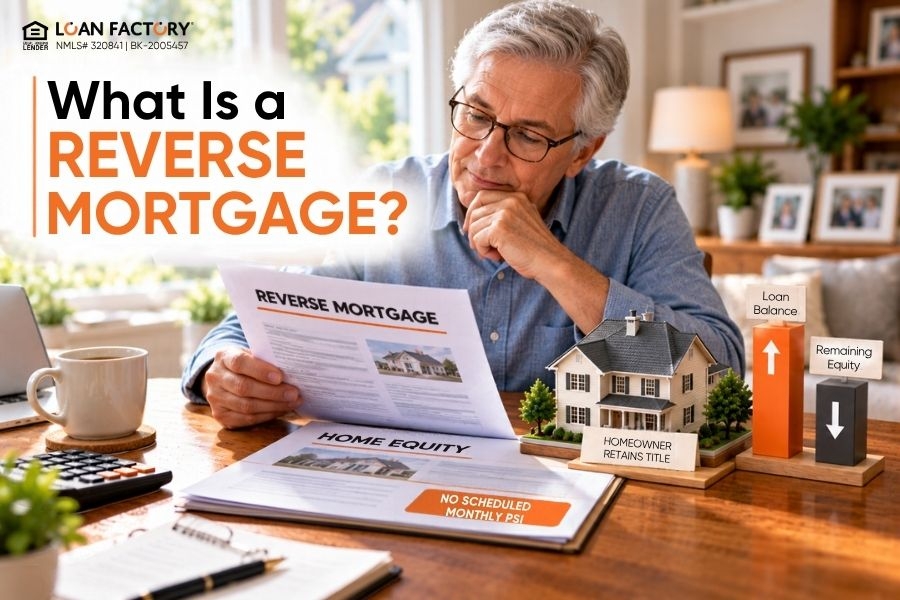
A reverse mortgage is still a loan secured by the home. Interest and fees are generally added to the balance over time, reducing the homeowner’s remaining equity. The loan normally becomes due after the last applicable borrower dies, sells the home, permanently moves out, or fails to satisfy important loan obligations.
Key Takeaways HECM, proprietary, and single-purpose loans are the main reverse mortgage categories. A HECM is an FHA-insured reverse mortgage for eligible homeowners age 62 or older. HECMs are available only through FHA-approved lenders. Proprietary reverse mortgages are private loans and are not federally insured. Proprietary products may be designed for homeowners with higher-value properties. Single-purpose reverse mortgages can be used only for the expense approved by the program. “Reverse annuity mortgage” is generally an older descriptive term rather than a separate modern federal loan category. Reverse mortgage proceeds may be available through a lump sum, line of credit, monthly advances, or a permitted combination, depending on the product. Borrowers generally retain title to the home. A reverse mortgage usually does not require monthly principal-and-interest payments while loan obligations are met. Borrowers must continue paying property taxes, homeowners insurance, and other applicable property charges. The home must generally remain the borrower’s principal residence and be maintained in acceptable condition. HECM counseling through an approved counselor is generally required before closing. Reverse mortgages can have substantial upfront and ongoing costs. Heirs may keep the home by satisfying the reverse mortgage balance under the applicable loan rules. A reverse mortgage is not appropriate for every homeowner or every retirement plan. Important: This article provides general education. Proprietary and single-purpose loan requirements vary widely by lender, state, local agency, nonprofit provider, property, and borrower. Review the actual loan documents and obtain independent counseling before making a decision.
What Is a Reverse Mortgage? A reverse mortgage is a home loan that allows an eligible homeowner to borrow against home equity.
For a broader explanation of repayment, costs, borrower responsibilities, risks, and long-term equity impact, see our guide to what a reverse mortgage is and how it works .
Unlike a traditional mortgage, the borrower generally does not make required monthly principal-and-interest payments while continuing to satisfy the loan’s occupancy and property obligations. Instead, advances, interest, mortgage insurance when applicable, and other fees are added to the loan balance. As the balance increases, the homeowner’s remaining equity generally decreases.
The homeowner usually retains legal title to the property. The lender does not become the owner merely because a reverse mortgage is recorded against the home.
The loan usually becomes due when a triggering event occurs, such as:
The home is sold The last applicable borrower dies The borrower permanently moves out The property is no longer the borrower’s principal residence Property taxes or homeowners insurance are not paid The home is not maintained as required Another material loan obligation is violated These repayment triggers and borrower responsibilities are especially important for FHA-insured HECMs.
Reverse Mortgage Types at a Glance Reverse mortgage type
Provider or insurer
Typical borrower or purpose
Federal insurance
FHA HECM FHA-approved private lender; insured by FHA Eligible homeowners age 62 or older Yes Proprietary reverse mortgage Private lender Often designed for higher-value properties or lender-specific needs No Single-purpose reverse mortgage Some state or local agencies and nonprofits A specific approved expense, such as repairs or property taxes No Reverse annuity mortgage Older descriptive terminology or payment arrangement Regular advances, sometimes associated with an annuity structure Depends on the underlying loan
The CFPB currently identifies FHA-insured HECMs, proprietary loans, and single-purpose loans as the principal reverse mortgage categories.
1. FHA Reverse Mortgage: Home Equity Conversion Mortgage A Home Equity Conversion Mortgage, or HECM, is the FHA reverse mortgage program.
HECMs are:
Insured by the Federal Housing Administration Available through FHA-approved lenders Generally available to eligible homeowners age 62 or older Secured by the borrower’s principal residence Subject to HUD counseling, financial assessment, appraisal, property, and servicing requirements HUD states that a HECM is the only reverse mortgage insured by the U.S. federal government.
Basic HECM Eligibility An applicant generally must:
Be at least 62 years old Own the home or have sufficient equity Occupy the property as a principal residence Complete required HUD-approved HECM counseling Satisfy financial assessment requirements Be able to meet ongoing property obligations Use an eligible property Pay off or otherwise resolve existing mortgage debt at closing Final eligibility depends on HUD rules, lender underwriting, property value, current mortgage balances, and other financial considerations.
For a deeper look at age, equity, financial assessment, credit, federal debt, property condition, and other factors that may affect qualification, see What Disqualifies You From Getting a Reverse Mortgage?
What Is the HECM Financial Assessment? A reverse mortgage lender does not review the borrower in exactly the same way as a traditional forward mortgage, but it still evaluates financial capacity.
The HECM financial assessment can examine:
Credit history Income Assets Monthly expenses Property taxes Homeowners insurance HOA or condominium charges Other recurring property costs Residual income The review helps determine whether the homeowner appears able to continue paying property charges. In some cases, part of the available loan proceeds may need to be reserved to pay future taxes and insurance.
HECM Property Requirements An eligible HECM property may include certain:
Single-family homes Owner-occupied two- to four-unit properties FHA-approved condominium units Manufactured homes meeting applicable requirements The property must generally be the borrower’s principal residence and satisfy FHA appraisal and property standards.
HECM Counseling Before proceeding with an FHA-insured HECM, the borrower generally must complete counseling with a HUD-approved HECM counselor.
Counseling is intended to explain:
How reverse mortgages work Loan alternatives Estimated costs Borrower obligations Available payment structures Effects on home equity Repayment events Considerations involving spouses and heirs HUD maintains a roster of approved HECM counselors.
HECM Payment Options The amount available generally depends on factors including:
Age of the youngest applicable borrower Current interest rates Home value Existing mortgage balance Program limits Selected payout method Closing costs and required set-asides Depending on the rate structure and current program rules, HECM proceeds may be available through:
A lump-sum payment A line of credit Regular monthly payments A combination of monthly payments and a credit line The CFPB identifies a line of credit, monthly payout, and lump-sum payout as the three main HECM distribution approaches.
HECM Tenure Payments A tenure payment plan generally provides equal monthly advances while the borrower continues occupying the property as a principal residence and complies with the loan requirements.
“Tenure” does not mean the homeowner receives unlimited money. The available monthly amount is calculated from the HECM principal limit and other program factors.
HECM Term Payments A term payment plan provides monthly advances for a selected number of months.
A borrower might select a term structure when funds are needed for:
A defined retirement-income gap A temporary period before other benefits begin Scheduled care expenses A specific multiyear financial need After the selected payment period ends, the borrower may remain in the home while continuing to satisfy the loan obligations, but the scheduled monthly advances stop.
HECM Line of Credit A HECM line of credit allows eligible borrowers to request advances from the available credit amount as needed.
This structure may be considered by homeowners who want:
Emergency access to equity Funds for future repairs A retirement cash-flow reserve Greater control over when loan advances occur The unused portion of a HECM credit line may follow program-specific growth provisions. This is not investment growth, interest earned by the homeowner, or an increase in the property’s actual equity.
Modified Tenure and Modified Term A borrower may be able to combine:
Tenure payments with a credit line Term payments with a credit line The monthly payment is generally reduced because part of the principal limit is reserved for the credit line. HUD’s HECM materials recognize tenure, term, line-of-credit, modified-tenure, and modified-term arrangements.
HECM for Purchase A HECM for Purchase allows an eligible older buyer to use reverse mortgage financing toward the purchase of a new principal residence.
The buyer must generally contribute enough eligible funds to cover the difference between:
The home’s purchase price and transaction costs The available HECM proceeds HUD confirms that HECM financing may be used to purchase a principal residence when the buyer can provide the required monetary investment and closing funds.
A HECM for Purchase may be considered by a homeowner who wants to:
Sell an existing home and move Downsize Relocate closer to family Purchase a more accessible property Avoid taking on a traditional required monthly mortgage payment The borrower must still maintain property taxes, insurance, occupancy, and the home’s condition.
HECM Costs A HECM can include:
Loan origination fee FHA initial mortgage insurance premium Ongoing mortgage insurance Appraisal Title search and title services Recording charges Credit review Inspection or survey costs Servicing-related charges when applicable Interest added to the outstanding balance The CFPB notes that reverse mortgages are typically more expensive than other home loans and that origination, third-party closing costs, and FHA mortgage insurance may apply.
Borrowers may be able to finance eligible closing costs using reverse mortgage proceeds. Doing so reduces the net amount available for other purposes and causes those financed charges to accrue interest.
HECM Non-Recourse Protection A HECM is structured as a non-recourse loan.
In general, this means the borrower or estate is not required to repay more than the applicable loan balance or property value under HECM rules, and assets other than the home are not used to satisfy the HECM debt.
When the balance exceeds the property value, FHA mortgage insurance helps address the eligible difference.
For heirs seeking to retain a HECM-financed home, applicable rules may allow satisfaction of the debt for the lesser of the loan balance or a percentage of the appraised value when the balance exceeds the home’s value. Specific deadlines and servicing procedures apply.
2. Proprietary Reverse Mortgage A proprietary reverse mortgage is a private reverse mortgage developed and offered by a lender or private financial institution.
It is not insured by FHA and does not automatically follow every HECM rule.
Proprietary products are often designed for borrowers with higher-value properties who may be able to access more equity than is available through the HECM structure.
Proprietary Reverse Mortgage Features Depending on the lender, a proprietary program may have different:
Minimum borrower age Maximum property value considered Loan amount Interest-rate structure Payment options Property types Credit standards Financial assessment rules Counseling requirements Non-borrowing spouse protections Non-recourse provisions Closing costs Because these are private products, terms can differ substantially among lenders.
Potential Advantages A proprietary reverse mortgage may offer:
Higher proceeds for certain higher-value homes Alternative property eligibility Different age requirements A structure not constrained by the HECM maximum claim amount Lender-specific lump-sum or credit-access options Availability is not guaranteed, and not every private program offers all these features.
Potential Disadvantages Potential considerations include:
No FHA insurance Fewer standardized federal program protections Limited lender availability Higher or differently structured costs Different spouse and heir provisions Less flexibility in payout choices State-specific restrictions More reliance on the lender’s contractual terms Before selecting a proprietary loan, compare its written protections with a HECM rather than focusing only on the maximum proceeds.
Questions to Ask a Proprietary Lender Is the loan non-recourse? What borrower age is required? What property types are eligible? Is counseling required? What happens if one spouse is not a borrower? When does the loan become due? What protections apply to heirs? Are funds available as a line of credit, lump sum, or monthly advances? Is the rate fixed or adjustable? What costs are added to the loan balance? Can the unused credit amount change over time? What happens if the lender or servicer transfers the loan? 3. Single-Purpose Reverse Mortgage A single-purpose reverse mortgage is a specialized loan that may be offered by a state or local government agency or nonprofit organization.
The proceeds can be used only for the purpose approved by the provider, such as:
Property taxes Necessary home repairs Accessibility modifications Safety improvements Energy-efficiency work Another specified housing expense Single-purpose loans may be available only in certain communities and may be limited to homeowners with low or moderate incomes. They are not federally insured HECMs.
Potential Benefits Single-purpose reverse mortgages may have:
Lower fees Lower interest costs A smaller loan balance A targeted public-service purpose Income-based eligibility Terms designed for aging in place The FTC describes single-purpose products as generally the least expensive reverse mortgage option, although availability is limited and proceeds can be used only for the lender-approved purpose.
Potential Limitations A single-purpose program may:
Be unavailable in your location Restrict how every dollar is used Require contractor approval Pay vendors directly Impose income or age limits Require the home to remain owner-occupied Become due after sale, transfer, death, or loss of primary occupancy Create a lien that affects future refinancing or sale Homeowners should contact their state housing agency, local housing department, Area Agency on Aging, property-tax office, or approved nonprofit organization to learn whether a program exists.
What Is a Reverse Annuity Mortgage? The term reverse annuity mortgage is an older phrase sometimes used to describe a reverse mortgage that provides recurring payments to the homeowner.
It is not one of the three main reverse mortgage product categories currently identified by the CFPB. A loan marketed with this phrase should be examined to determine whether it is actually:
An FHA-insured HECM A proprietary reverse mortgage A single-purpose loan A reverse mortgage connected to a separately purchased annuity A monthly tenure or term payment arrangement This distinction is an inference from the CFPB’s current product classifications and federal reverse mortgage disclosure rules.
Reverse Mortgage vs. Annuity A reverse mortgage and an annuity are different financial products.
A reverse mortgage is a loan secured by the home. An annuity is generally an insurance contract intended to make payments according to its terms. Some historical or private arrangements may use reverse mortgage proceeds to purchase an annuity. Federal disclosure rules account for annuity payments when the annuity is purchased as part of the reverse mortgage transaction.
Purchasing an annuity with reverse mortgage proceeds can add:
Annuity fees Surrender charges Reduced liquidity Additional complexity Questions about suitability Different tax considerations A borrower should not purchase an annuity merely because a reverse mortgage representative recommends it. Consider receiving independent legal, tax, insurance, and financial guidance.
Comparing the Main Types of Reverse Mortgage Feature
FHA HECM
Proprietary reverse mortgage
Single-purpose reverse mortgage
Federal insurance FHA-insured No No Typical age 62 or older Lender-specific Program-specific Use of proceeds Generally flexible Product-specific Restricted Higher-value home option Limited by HECM framework Often a primary use Usually not the focus Counseling HUD-approved counseling generally required Varies Varies Payment options May include lump sum, credit line, or monthly advances Varies Usually tied to approved expense Availability Through FHA-approved lenders Selected private lenders Limited local programs Primary residence Required Usually required; verify Usually required Mortgage insurance FHA mortgage insurance Product-specific Generally none Standardization Extensive federal rules Lender-specific contract Agency-specific rules
Which Reverse Mortgage Type May Fit? Consider a HECM When: You are at least 62. You want FHA-insured protections. The home fits HECM property requirements. You want multiple potential payout structures. You can continue paying taxes, insurance, and property charges. You are willing to complete HUD-approved counseling. Consider a Proprietary Loan When: The property value is high. HECM proceeds may not address your financing objective. A private program offers suitable terms. You understand that FHA insurance does not apply. You have compared spouse, heir, non-recourse, and servicing protections carefully. Explore a Single-Purpose Loan When: You need funds for one specific housing expense. Your local government or nonprofit offers a program. You meet its income, age, and property requirements. The restricted use of funds meets your objective. Lower costs are more important than broad access to cash. Borrower Responsibilities A HECM borrower generally must:
Occupy the property as a principal residence Pay property taxes and homeowners insurance on time Pay other applicable property charges Maintain the home in acceptable condition Respond to annual occupancy certifications and servicer requests Failure to meet these obligations may cause the loan to become due and payable and can lead to foreclosure.
Applicable property charges may include:
Property taxes Homeowners insurance Flood insurance Ground rent Condominium fees HOA dues Certain special assessments Proprietary and single-purpose products may have similar or additional obligations. Review the actual agreement.
What Happens to the Existing Mortgage? An existing first mortgage generally must be paid off when a reverse mortgage closes.
The payoff usually comes from:
Reverse mortgage proceeds The homeowner’s cash A combination of proceeds and cash If the existing mortgage and closing costs use a large portion of the available principal limit, the homeowner may receive little remaining cash.
This calculation should be completed before paying for an appraisal or making irreversible financial plans.
What Happens to Heirs? A reverse mortgage does not automatically prevent heirs from inheriting the home.
After the applicable borrower and protected spouse provisions end, heirs may generally:
Pay off the reverse mortgage and keep the home Obtain new financing to satisfy the balance Sell the property and use the proceeds to repay the loan Transfer the property to the lender under applicable procedures For HECMs, servicing deadlines apply after the loan becomes due and payable. Heirs should contact the servicer promptly and obtain instructions in writing.
If the property is worth more than the loan balance, the remaining equity generally belongs to the homeowner or estate after the mortgage and sale costs are paid.
Reverse Mortgage Benefits Potential benefits may include:
Access to home equity No required monthly principal-and-interest payment while obligations are met Ability to remain in the home Paying off an existing mortgage Creating a credit line for future needs Receiving regular monthly advances Funding home repairs or accessibility improvements Using a HECM toward a new principal residence HECM non-recourse protection These are potential features, not guaranteed financial outcomes.
Reverse Mortgage Risks Equity Declines Over Time Interest and fees are added to the balance, so the amount owed generally increases while remaining equity decreases.
Costs Can Be Significant Reverse mortgage closing costs can make the loan less practical for someone who expects to sell or move soon.
Taxes and Insurance Remain Due Eliminating a traditional monthly mortgage payment does not eliminate:
Property taxes Insurance HOA dues Repairs Maintenance Special assessments Foreclosure Is Possible A reverse mortgage can enter default when required property charges are not paid, the home is no longer the principal residence, or maintenance obligations are not met.
Spouse Protections Can Be Complicated A spouse who is not a co-borrower may have different rights from a borrower. HECM protections for an eligible non-borrowing spouse depend on HUD requirements and the facts of the loan.
Public Benefits May Be Affected Loan proceeds generally are not treated the same as ordinary earned income, but funds retained in an account may affect asset-tested public benefits.
Borrowers receiving Medicaid, Supplemental Security Income, or another needs-based program should consult the appropriate benefits specialist before selecting a payout method.
Scams and High-Pressure Sales Be cautious when someone:
Claims the loan is free government money Pressures you to sign immediately Requires you to purchase an investment or annuity Discourages independent counseling Requests money before explaining the product Says you cannot lose the home under any circumstances Contacts you using an official-looking government identity Reverse mortgages are loans, not government grants.
Alternatives to a Reverse Mortgage Before borrowing, compare:
Selling and moving to a less expensive home Traditional home equity loan HELOC Cash-out refinance Property-tax deferral programs Home repair grants Single-purpose assistance Budget changes Family support Renting part of the home when permitted Local aging-in-place programs A home equity loan or HELOC generally requires monthly payments, but it may have lower upfront costs for a short-term borrowing need. Learn more about the differences between a home equity loan vs. HELOC .
How to Compare Reverse Mortgage Offers Ask each lender for written information covering:
Loan type Interest rate Fixed or adjustable structure Principal limit Initial proceeds Existing mortgage payoff Mortgage insurance Origination charge Third-party closing costs Required set-asides Payout method Total Annual Loan Cost disclosures Non-recourse protection Repayment triggers Spouse protections Servicing contact information Do not compare offers based only on the gross principal limit. The more useful figure is the net amount available after mortgage payoff, fees, insurance, and required reserves.
How to Apply for a Reverse Mortgage Step 1: Define Your Goal Determine whether the objective is to:
Pay off an existing mortgage Create emergency liquidity Fund necessary repairs Improve retirement cash flow Purchase a new home Remain in the property longer Step 2: Compare All Three Product Categories Check whether an FHA HECM, proprietary loan, or lower-cost single-purpose program may fit the goal.
Step 3: Review the Household and Title Structure Identify:
All property owners Borrowers Spouses Non-borrowing spouses Trust ownership Heirs Existing liens Step 4: Complete Counseling HECM borrowers generally must complete HUD-approved counseling before closing.
Step 5: Submit the Application Common documents may include:
Identification Proof of age Current mortgage statement Property-tax bill Homeowners insurance HOA statement Trust documents Income and asset records Counseling certificate For broader document preparation, use our mortgage application document checklist to organize common financial and property records before submitting an application.
Step 6: Complete Appraisal and Financial Assessment The lender reviews the property, existing liens, financial capacity, and continuing ability to pay property charges.
Step 7: Review Proceeds and Costs Confirm how much remains after:
Existing mortgage payoff Initial mortgage insurance Origination fee Closing costs Repair reserves Tax and insurance set-asides Step 8: Review the Final Loan Documents Do not sign until you understand:
When repayment is required How the balance grows Which rate can change What happens to a spouse What heirs must do Which obligations can trigger default For a more detailed walkthrough of eligibility, counseling, documentation, appraisal, financial assessment, and closing, see our step-by-step guide on how to apply for a reverse mortgage .
Loan Factory offers reverse mortgage scenario reviews for eligible homeowners seeking to understand FHA-insured HECM options. Its reverse mortgage process includes an initial eligibility review, required counseling, lender comparison, appraisal, financial assessment, and closing review.
Loan Factory’s licensed mortgage professionals can help homeowners:
Compare available FHA-approved reverse mortgage structures Estimate how an existing mortgage payoff affects net proceeds Review lump-sum, monthly-payment, and line-of-credit scenarios Understand property-tax and insurance responsibilities Prepare for required HUD counseling Review HECM for Purchase scenarios Compare a reverse mortgage with HELOC or home equity alternatives Upload documents and follow loan milestones through TERA Availability depends on borrower age, equity, property, occupancy, financial assessment, counseling, state licensing, FHA requirements, and participating lender guidelines.
Explore Reverse Mortgage Options Review whether an FHA-insured HECM may fit your home equity and long-term housing plan.
Explore reverse mortgage options
Compare Home Financing Alternatives Compare a reverse mortgage with other available mortgage or home equity structures before making a final decision.
Compare mortgage options
A reverse mortgage review is not approval or a recommendation that the product is appropriate for every homeowner.
Experience Note A productive reverse mortgage review should compare the net usable proceeds, not only the estimated maximum loan amount.
Ask the lender to show:
Gross principal limit Existing mortgage payoff Initial mortgage insurance Origination and third-party costs Repair or property-charge set-asides Initial cash available Future credit or monthly advances Estimated loan balance over time Remaining projected equity Amount heirs may need to keep the home This makes it easier to understand the long-term tradeoff between receiving equity now and preserving equity for a future move or inheritance.
Author Box Written by: Loan Factory Mortgage Education Team
Loan Factory is a technology-powered mortgage platform helping homeowners compare reverse mortgage and home equity options through a broad wholesale lender network. Our mortgage education team helps borrowers understand FHA HECMs, proprietary reverse mortgages, single-purpose loans, payout structures, counseling, property obligations, costs, repayment events, and considerations for spouses and heirs.
Mortgage Disclaimer This content is for educational and informational purposes only. It is not legal, tax, estate-planning, insurance, investment, public-benefits, retirement-planning, housing-counseling, or financial advice and is not a commitment to lend or a guarantee of eligibility, approval, proceeds, interest rate, payment option, property value, non-recourse protection, or closing.
Reverse mortgage eligibility, costs, proceeds, payout structures, spouse protections, heir options, and repayment requirements depend on borrower age, property value, equity, existing liens, occupancy, financial assessment, counseling, property condition, lender, product, state law, federal rules, and current program guidelines.
A reverse mortgage is a loan secured by the home. Interest and fees generally increase the loan balance and reduce remaining equity. Failure to meet occupancy, tax, insurance, maintenance, or other loan requirements may lead to default and foreclosure.
Loan Factory is not a government agency and is not affiliated with or acting on behalf of HUD, FHA, the Consumer Financial Protection Bureau, the Federal Trade Commission, or another government entity.
Loan Factory, Inc. | NMLS #320841 | Equal Housing Lender.
Frequently Asked Questions