The mortgage underwriting process timeline begins after the lender receives your application and supporting documents. An underwriter then verifies your income, employment, assets, debts, credit history, property value, and loan-program eligibility before deciding whether the mortgage can proceed.
Some lenders may complete an initial underwriting review within one to three business days after receiving a complete file. However, this is not an industry-wide guarantee. The full underwriting process can take longer when borrowers must clear conditions, update documents, resolve appraisal or title issues, or complete multiple review rounds.
Key Takeaways Mortgage underwriting verifies both your ability to repay and the property’s eligibility for the proposed loan. A complete initial underwriting review may take one to three business days, but that is not the same as reaching clear to close. Most files receive conditional approval before final approval. Each new document, financial change, property issue, or underwriting condition can add another review cycle. Responding quickly helps, but borrowers cannot control lender workload, appraisal timing, title issues, or third-party verifications. Clear to close means required underwriting conditions have been accepted, but signing, funding, and recording may still remain. For most covered transactions, the borrower generally must receive the Closing Disclosure at least three business days before closing. Important Note: Underwriting timelines, documentation, approval conditions, appraisal requirements, lender turn times, and closing procedures vary by borrower, lender, mortgage program, property, location, market volume, and underwriting findings. This article is informational and is not a commitment to lend or a closing-time guarantee.
What Is Underwriting for a Mortgage Loan? Mortgage underwriting is the lender’s process for verifying whether the borrower, property, and proposed mortgage satisfy applicable credit, income, asset, collateral, loan-program, and investor requirements.
Freddie Mac explains that underwriting includes verifying employment, income, assets, debts, and credit history. The underwriter also evaluates whether the mortgage amount is reasonable in relation to the property’s value.
The underwriter is generally trying to answer three core questions:
Can the borrower reasonably repay the mortgage? Does the property provide acceptable collateral? Does the loan comply with the selected program and lender requirements? What Is Home Loan Underwriting? Home loan underwriting is another name for mortgage underwriting.
The process applies to purchase and refinance transactions. Although the documents and property review may differ, the lender still needs to verify the borrower’s financial information, assess the property, and determine whether the proposed loan satisfies applicable guidelines.
How Long Does Mortgage Underwriting Take? The initial mortgage underwriting review may take a few business days, depending on the lender's workload, file completeness, and loan complexity. This initial review is only one part of the full underwriting timeline.
According to Loan Factory's published loan process, a participating lender may issue an initial decision within one to three days. This decision may be a conditional approval, suspension, or denial rather than final approval. Actual turnaround times vary by lender and file.
Practical Planning Range As a planning estimate—not a guaranteed service timeline:
File situation
Possible underwriting experience
Complete, straightforward file Initial review may occur within a few business days File with standard conditions Additional days may be needed for document collection and re-review Self-employed or complex income Multiple review rounds may be required Appraisal, title, condo, or insurance issue Timeline may extend until the issue is resolved Changed income, credit, assets, or loan terms File may need to be re-underwritten Incomplete or inconsistent documents Review may pause until acceptable information is received
The CFPB advises borrowers to expect additional document requests during underwriting and to respond quickly. It also warns against submitting incomplete statements because missing pages can delay verification.
Initial Review Is Not the Entire Timeline When someone says underwriting takes two or three days, they may be referring only to the first underwriter review.
The complete cycle may involve:
Processor preparation Automated underwriting findings Initial underwriter review Conditional approval Borrower document collection Appraisal and title updates Condition resubmission Final underwriter review Clear to close Closing-document preparation A file can return to underwriting more than once before the lender issues final approval.
Mortgage Underwriting Process Timeline at a Glance Stage
What happens
What can affect timing
1. Application and document collection The lender receives borrower and property information Missing or outdated documents 2. Loan processing The processor reviews and organizes the file Inconsistencies, incomplete pages, unverified funds 3. Automated underwriting The lender runs the file through an underwriting system when applicable Data accuracy and program eligibility 4. Property and third-party review Appraisal, title, insurance, and project documents are reviewed Scheduling, repairs, title issues, insurance 5. Initial underwriting decision The underwriter approves, conditions, suspends, or denies the file File complexity and lender workload 6. Condition clearing Borrower and third parties provide requested information Response time and document acceptability 7. Final approval and clear to close Conditions are accepted and closing preparation begins Final verifications and disclosure timing
Each stage can overlap with another. For example, the appraisal may be in progress while the underwriter reviews income and assets.
Stage 1: Complete the Mortgage Application The underwriting process needs accurate borrower, property, income, asset, debt, and loan information.
A typical mortgage application includes:
Borrower identity Employment history Income sources Assets Current debts Real estate owned Property address Purchase price or estimated property value Down payment Intended occupancy Loan purpose Fannie Mae advises applicants to prepare documents supporting income, assets, employment, and other personal financial information.
Common Starting Documents Depending on the borrower and program, the lender may request:
Recent pay stubs W-2 or 1099 forms Personal and business tax returns Bank statements Investment or retirement statements Identification Purchase contract Earnest-money documentation Gift-fund records Rental-income records Mortgage statements Homeowners insurance information Submitting a document does not necessarily mean the underwriter will accept the income, asset, or transaction exactly as presented. The information must satisfy the selected program’s documentation and eligibility requirements.
First-time buyers can use our first-time homebuyer document checklist to organize common paperwork before underwriting.
Stage 2: Loan Processing and File Preparation Before a loan reaches the underwriter, the processor generally reviews the application and documents for completeness.
The processor may:
Organize income and asset documents Review the purchase contract Identify missing statements Request employment verification Confirm earnest-money documentation Order title work Coordinate the appraisal Request homeowners insurance Review applicable program forms Prepare the file for underwriting Processing and underwriting are related but different.
Loan processor
Mortgage underwriter
Collects and organizes documents Evaluates eligibility and risk Identifies missing information Issues the underwriting decision Communicates document requests Determines whether conditions are satisfied Coordinates third-party items Confirms compliance with loan guidelines Prepares the file for review Approves, conditions, suspends, or denies
A well-prepared file can help the underwriter reach a decision without repeatedly returning it for missing basic information.
Stage 3: Automated Underwriting Review Many conventional and government-backed mortgage applications are evaluated with assistance from an automated underwriting system.
Examples include:
Fannie Mae Desktop Underwriter® Freddie Mac Loan Product Advisor® Applicable government or lender underwriting systems Fannie Mae explains that lenders use Desktop Underwriter to assess mortgage credit risk and determine whether a loan may be eligible for sale to Fannie Mae. The lender must still confirm that the application information is accurate and retain supporting documentation.
Automated Underwriting Is Not Final Approval An automated recommendation does not replace:
Document verification Appraisal review Title review Insurance review Fraud and compliance checks Underwriter judgment Lender overlays Final condition review The automated findings may identify:
Required income documents Required asset documents Reserve requirements Appraisal requirements Eligibility issues Additional verification needs A favorable automated finding can help structure the file, but the loan still must satisfy all applicable conditions.
Stage 4: Property, Appraisal, Title, and Insurance Review Mortgage underwriting includes the property because the home serves as collateral for the loan.
Freddie Mac explains that the underwriter evaluates the property’s appraised value in addition to the borrower’s financial capacity.
Appraisal Review The lender may evaluate:
Appraised value Property condition Comparable sales Required repairs Legal use Unit count Marketability Loan-to-value ratio Program-specific property requirements An appraisal delay can hold up final approval even when the borrower’s financial review is complete.
The appraised value can also affect the loan-to-value ratio , which is an important factor in mortgage underwriting.
Title Review Title work can identify:
Existing mortgages Tax liens Judgments Ownership issues Easements Unreleased liens Recording problems Legal description concerns The lender may require title issues to be resolved before closing.
Insurance Review The lender may need to confirm:
Homeowners insurance coverage Coverage amount Deductible Effective date Flood insurance when required Condo master insurance Additional hazard coverage Lender information on the policy A borrower should begin shopping for insurance early rather than waiting until underwriting is nearly complete.
Stage 5: Initial Underwriting Decision After reviewing the borrower, property, documents, and loan structure, the underwriter issues an initial decision.
The most common outcomes are:
Decision
What it generally means
Conditional approval The loan may proceed after the listed requirements are satisfied. Approved The reviewed file satisfies the current approval requirements. Suspended or pending The underwriter cannot decide without additional material information. Denied The loan does not meet applicable requirements based on the reviewed information.
Loan Factory’s public process explains that a lender may conditionally approve a file and provide a list of requirements that must be satisfied before final approval.
Conditional Approval Is Normal A conditional approval does not necessarily indicate that something is wrong.
It often means the lender has completed a substantial review but still needs items such as:
Updated pay stubs Updated bank statements Final employment verification Gift documentation Explanation of a deposit Insurance evidence Appraisal corrections Title documentation HOA or condo records Proof that a debt was paid Final purchase-contract addenda The loan is not clear to close until the lender confirms that all required prior-to-closing conditions have been satisfied.
Stage 6: Clear Underwriting Conditions After conditional approval, the processor and Loan Officer help collect the requested documents and return them to the lender.
The CFPB advises borrowers to:
Ask exactly how documents should be submitted. Provide complete copies. Keep original documents. Confirm receipt. Monitor email, voicemail, and mail. Respond quickly to additional requests. Why Does the Underwriter Ask for More Documents? The underwriter may need to:
Update an expired document. Resolve inconsistent information. Verify the source of funds. Confirm that income will continue. Document a large deposit. Explain a credit inquiry. Confirm a debt payment. Review new property information. Verify an employment change. Confirm compliance with program guidelines. An additional request does not automatically mean the loan is in trouble.
However, the requested document must answer the underwriter’s question. Sending unrelated records can create another review round without clearing the condition.
Condition-Review Cycle The process commonly works like this:
Underwriter issues conditional approval. Processor explains the outstanding conditions. Borrower or third party provides documents. Processor reviews the documents for completeness. File returns to the underwriter. Underwriter clears, updates, or adds conditions. Process repeats until all required items are accepted. Every incomplete response can add another cycle.
Preparing for underwriting? Review the Loan Factory loan process to understand the steps from application through final approval and closing.
Stage 7: Final Approval and Clear to Close Clear to close generally means the lender has accepted the required underwriting conditions and can proceed with closing preparation.
This is an important milestone, but the transaction is not yet funded or recorded
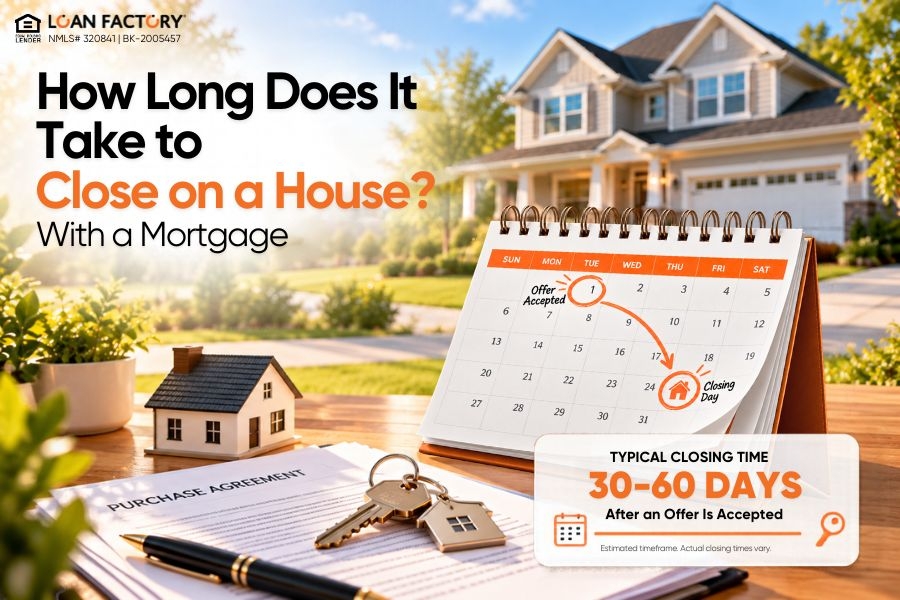
For a broader look at what happens before closing, read our guide on how long it takes to close on a house with a mortgage .
Remaining steps can include:
Final loan-document preparation Closing Disclosure delivery Final employment or financial verification Confirmation of homeowners insurance Verification of cash to close Signing Lender review of executed documents Funding Title disbursement and recording Loan Factory’s published process notes that after the lender approves the executed documents and completes required final verification, funds can be sent to the title company for disbursement and recording.
The Three-Business-Day Closing Disclosure Period For most covered mortgage transactions, the borrower generally must receive the Closing Disclosure at least three business days before the scheduled closing.
The Closing Disclosure provides final information about:
Loan amount Interest rate Monthly payment Closing costs Lender credits Seller credits Cash to close Escrow details Other loan terms The CFPB recommends comparing the Closing Disclosure with the most recent Loan Estimate and asking about unexplained changes before signing.
What Does an Underwriter Review? The underwriter evaluates the complete risk profile rather than relying on one credit score, income figure, or down payment amount.
Income and Employment The lender may verify:
Current employment Employment history Salary or hourly income Overtime, bonus, or commission income Self-employment income Rental income Retirement or benefit income Other eligible recurring income Likelihood that income will continue Income must be documented according to the selected mortgage program.
Credit and Debts The underwriter may review:
Credit reports Payment history Credit scores Credit-card balances Student loans Auto loans Personal loans Support obligations Other mortgages Recent inquiries Public records or major credit events The lender uses eligible monthly obligations to evaluate the debt-to-income ratio and overall repayment capacity.
Assets and Funds The lender may verify:
Down payment Closing costs Reserves Earnest money Gift funds Assistance funds Sale proceeds Transfers Large deposits Business funds Retirement or investment assets The CFPB notes that lenders generally need to verify the source of income and down payment funds, including certain large deposits and account transfers.
Property and Collateral The underwriter may consider:
Appraised value Property condition Property type Occupancy Legal use Title Insurance HOA or condo eligibility Flood status Loan-to-value ratio The borrower may qualify financially while the property fails to satisfy the selected mortgage program.
What Can Delay Mortgage Underwriting? Underwriting is commonly delayed by incomplete documents, changed finances, complex income, or unresolved property issues.
Borrower Documentation Delays Missing bank-statement pages Outdated pay stubs Unsigned tax returns Unverified deposits Missing gift documentation Incomplete employment history Unexplained credit inquiries Unreported debts Income Complexity Self-employment Multiple businesses Commission or bonus income Overtime Rental properties Seasonal employment Recently changed jobs Income decline Foreign income Multiple tax-return schedules Asset and Fund Issues Large cash deposits Money transferred without a paper trail Business funds used at closing Gift funds transferred incorrectly Funds borrowed without disclosure Cryptocurrency conversion Asset statements that become outdated Property Issues Appraisal below the purchase price Required repairs Unpermitted additions Title liens Condo approval concerns Insufficient insurance Flood insurance requirements HOA litigation Incorrect property classification Transaction Changes Different purchase price Changed down payment New seller credit Different loan program Revised loan amount Changed occupancy New borrower Removed borrower Delayed closing date A significant change can require new disclosures, updated automated underwriting, revised documentation, or another underwriter review.
Does Underwriting Take Longer for Certain Loan Types? No loan type has one guaranteed underwriting timeline.
Conventional, FHA, VA, USDA, Jumbo, Non-QM, condo, renovation, and investment-property loans can each move quickly or slowly depending on the file.
Loan type or situation
Possible additional review
Conventional Automated findings, mortgage insurance, condo review FHA FHA borrower, property, appraisal, and mortgage-insurance requirements VA Eligibility, entitlement, appraisal, residual-income, and VA requirements USDA Household income, property location, program and agency requirements Jumbo Additional reserves, asset, credit, and income review Non-QM Program-specific income and asset documentation Self-employed Tax returns, business income, P&L, and business liquidity Condo HOA, insurance, budget, litigation, and project eligibility Renovation Scope of work, contractor, bids, appraisal, and repair process
The number of conditions and the time needed to obtain third-party information usually matter more than the loan label alone.
For borrowers who need alternative income documentation, Non-QM loans may offer other qualification paths, subject to program and lender requirements.
How to Help the Underwriting Process Move Smoothly You cannot control every part of underwriting, but you can reduce preventable delays.
Submit Complete Documents Include every page. Use readable PDF files. Avoid cropped screenshots. Make sure your name, account, and statement period are visible. Follow the lender’s secure-upload instructions. Respond Quickly Check:
Email Text messages Voicemail TERA notifications Requests from your Loan Officer or processor Ask for clarification when a condition is unclear rather than guessing which document to send.
Keep Your Finances Stable Before funding, avoid:
Opening new credit Financing furniture or a car Co-signing another loan Changing jobs without notice Reducing work hours Moving large amounts without records Spending funds reserved for closing Closing verified bank accounts Making unexplained cash deposits Keep a Paper Trail Retain records for:
Account transfers Gift funds Earnest money Asset sales Debt payoffs Business-fund withdrawals Assistance funds Large deposits Start Third-Party Tasks Early Do not wait until final underwriting to begin:
Homeowners insurance Condo document collection Required inspections Repair verification Title issue resolution Gift documentation Mortgage Underwriting Do and Don’t Checklist Do Submit accurate application information. Provide complete documents. Explain unusual transactions. Keep closing funds available. Continue paying bills on time. Respond to requests promptly. Notify your Loan Officer about changes. Review updated disclosures. Don’t Open new credit without discussing it. Make large purchases. Change employment without notice. Deposit undocumented cash. Move funds repeatedly between accounts. Assume preapproval guarantees closing. Ignore a lender request. Wait until closing day to review loan terms. Can a Mortgage Be Denied During Underwriting? Yes. Preapproval and conditional approval do not guarantee final mortgage approval.
A loan may be denied or become ineligible when:
Income cannot be verified. Debt-to-income exceeds applicable requirements. Funds cannot be documented. Credit changes materially. Employment ends or changes. The property does not appraise adequately. Title or insurance issues remain unresolved. The borrower does not satisfy conditions. The loan does not meet program or lender requirements. Material information in the application is inaccurate. Loan Factory’s process explains that an initial underwriting decision may include denial or suspension when the borrower or file does not satisfy the lender’s requirements.
A lender should explain the decision and, when applicable, identify information needed to continue or reconsider the file.
Preapproval vs. Conditional Approval vs. Clear to Close Milestone
What it means
Is the loan final?
Prequalification Early estimate based on preliminary information No Preapproval Initial borrower review based on available information No Automated underwriting result System recommendation based on submitted data No Conditional approval The underwriter may approve after the listed conditions are met. No Final approval Required underwriting items have been accepted. Close, but closing steps remain Clear to close The lender can prepare the transaction for closing. Not funded yet Funded and recorded The lender sends funds, and ownership documents are completed. Transaction complete under local procedures
Understanding these milestones can prevent confusion when the lender says a file is “approved” but still requests additional documents. Learn more about What Is a Mortgage Pre-Approval? and why it is not the same as final approval.
How Loan Factory Helps During Underwriting Loan Factory is a technology-powered mortgage platform helping borrowers compare mortgage options through a broad wholesale lender network.
Depending on the loan, borrower, and participating lender, a Loan Factory Loan Officer and processing team can help:
Identify the documents required for the selected program. Review the file before lender submission. Explain underwriting conditions. Organize income and asset documentation. Coordinate appraisal and third-party items Communicate condition requests. Submit updated documents for review. Compare alternative mortgage options when a file needs restructuring Track available loan milestones through TERA. Through TERA, borrowers can complete an application, securely upload requested documents, communicate with their Loan Officer, and follow available mortgage milestones.
Compare mortgage options with Loan Factory, or call or text (660) 333-3333 to discuss your mortgage needs with a Loan Officer.
Plan for the Full Underwriting Cycle The mortgage underwriting process timeline is not limited to the underwriter’s first review.
A complete file may receive an initial decision within a few business days, but conditional approval, document collection, appraisal, title, insurance, re-review, and final verification can extend the process.
The best way to prepare is to submit complete documents, maintain stable finances, respond quickly, and resolve property or title concerns early.
Ready to take the next step? Apply for a mortgage online with Loan Factory to begin the application process.
Experience Note The timelines, stages, conditions, and process examples in this article are educational illustrations based on common mortgage processing, underwriting, appraisal, title, insurance, disclosure, and closing considerations.
They do not represent a guaranteed Loan Factory or lender timeline, a specific borrower, conditional approval, final approval, clear-to-close decision, closing, or funded transaction. Actual timelines and outcomes vary by borrower, lender, property, program, market volume, and underwriting findings.
Sources About the Author Loan Factory Mortgage Education Team
Loan Factory is a technology-powered mortgage platform helping borrowers compare mortgage options through a broad wholesale lender network.
The Loan Factory Mortgage Education Team helps homebuyers and homeowners understand mortgage processing, underwriting conditions, appraisal and title reviews, clear-to-close requirements, and the steps between application and funding.
Disclaimer This content is for educational and informational purposes only and is not financial, tax, legal, credit, accounting, real estate, appraisal, title, insurance, or housing-counseling advice. It is not a commitment to lend or a guarantee of preapproval, approval, underwriting timing, clear-to-close status, rates, APRs, payments, closing, or funding.
Mortgage documentation, underwriting requirements, lender turn times, appraisal procedures, title conditions, disclosure timing, and eligibility may change and vary by borrower, lender, property, occupancy, loan purpose, location, mortgage program, underwriting, and investor guidelines. Consult appropriately licensed professionals regarding your circumstances.
Frequently Asked Questions