Mortgage options for first time buyers include conventional loans with down payments as low as 3%, FHA-insured loans, VA-backed mortgages for eligible military borrowers, USDA-guaranteed loans for qualifying rural properties, and state or local assistance programs.
There is no single loan that is best for every first-time buyer. The right option depends on credit, income, debts, savings, military eligibility, property location, mortgage insurance, monthly payment, and how long the buyer expects to own the home.
Key Takeaways A first-time home buyer loan is not one separate mortgage product. Eligible buyers may compare conventional, FHA, VA, USDA, state housing agency, and down payment assistance programs. Certain conventional loans may allow a down payment as low as 3%. FHA financing may allow a 3.5% down payment and may provide more flexible credit options. VA loans may offer no-down-payment financing and no monthly mortgage insurance for eligible borrowers. USDA loans may offer 100% financing for eligible households and rural properties. First-time buyer status may provide access to special programs, but it does not guarantee approval, a grant, or more favorable pricing. The smallest down payment does not always produce the lowest monthly or long-term cost. Buyers should compare official Loan Estimates using the same loan amount, term, down payment, and rate-lock assumptions. Important Note: Mortgage programs, down payment requirements, mortgage insurance, credit standards, income limits, assistance funding, loan limits, rates, fees, and property eligibility vary by borrower, lender, program, property, location, underwriting, and investor guidelines. This article is for informational purposes only and is not a commitment to lend.
What Is a First-Time Home Buyer Loan? A first-time home buyer loan is a general term for mortgage options that may be available to someone buying a first home or meeting a program’s definition of a first-time buyer.
It is not one specific loan type.
A first-time buyer may use:
A conventional mortgage An FHA-insured mortgage A VA-backed mortgage A USDA-guaranteed mortgage A state housing finance agency loan A local assistance program An employer-supported benefit Another eligible lender or nonprofit program Some programs are specifically restricted to first-time buyers. Others, including FHA, VA, USDA, and HomeReady®, may also be available to eligible repeat buyers.
The Consumer Financial Protection Bureau identifies FHA, VA, USDA, Fannie Mae, and Freddie Mac programs among the mortgage options commonly used by first-time buyers.
Loan Factory’s guide to first-time home buyer home loan programs provides a broader overview of these program categories.
Who Is Considered a First-Time Home Buyer? A first-time buyer is often someone who has not owned residential property during the three years before purchasing the new primary residence. However, the exact definition depends on the mortgage or assistance program.
Fannie Mae’s standard 97% financing generally considers whether an occupying buyer owned residential property during the preceding three years. Certain exceptions may apply to a displaced homemaker or single parent who previously owned only with a spouse.
A program may also apply different rules to:
A buyer who owned an investment property Someone who inherited property A divorced or separated buyer A displaced homemaker A single parent A manufactured-home owner A buyer purchasing in a targeted area A Veteran using a state housing program Do not assume you are ineligible merely because you owned a home many years ago.
Mortgage Options for First Time Buyers at a Glance The main options differ in down payment, mortgage insurance, borrower eligibility, property location, and underwriting.
Mortgage option
Possible down payment
May fit buyers who
Conventional standard 97% 3% Have qualifying credit and at least one eligible first-time buyer HomeReady® 3% Meet applicable income and program requirements Home Possible® 3% Meet applicable income and affordable-lending requirements HomeOne® 3% Are qualified first-time buyers without an income or geographic limit FHA 3.5% Need a lower down payment or more flexible credit review VA Potentially 0% Have eligible military service or qualifying surviving-spouse status USDA Potentially 0% Meet income requirements and purchase an eligible rural property State or local program Varies Meet location, income, first-time buyer, and funding requirements Down payment assistance Varies Need help with down payment or closing costs
The CFPB recommends evaluating the loan type, loan term, and interest-rate structure separately because each decision can affect the down payment, monthly payment, borrowing cost, and property price range.
1. Conventional Loans for First-Time Buyers A conventional home loan is a mortgage that is not insured or guaranteed by FHA, VA, or USDA. Conforming conventional loans generally follow requirements established by Fannie Mae or Freddie Mac.
Conventional financing may be a strong option for a buyer with:
Stable documented income Acceptable credit Manageable debts Sufficient funds for the transaction A qualifying primary residence A financial profile that produces competitive conventional pricing Conventional loans may cost less than FHA financing for some borrowers, particularly when the buyer has stronger credit or a larger down payment. However, conventional qualification may be more restrictive in other situations.
Fannie Mae Standard 97% Financing Fannie Mae offers financing up to 97% of the property value for eligible standard purchase transactions when at least one borrower is a first-time buyer.
General features include:
Down payment as low as 3% At least one eligible first-time buyer One-unit principal residence Fixed-rate mortgage Desktop Underwriter® review Mortgage insurance when required Homeownership education in certain transactions Fannie Mae’s standard 97% option does not apply an income limit, although all credit, income, property, underwriting, and mortgage insurance requirements remain applicable.
HomeReady® HomeReady is a Fannie Mae mortgage designed for eligible low-income borrowers.
Potential features include:
Down payment as low as 3% Eligible gifts and grants Down payment assistance Community Seconds® financing Reduced mortgage insurance requirements for certain transactions Mortgage insurance that may be canceled when applicable requirements are satisfied HomeReady applies income and other eligibility requirements, but the borrower does not always have to be a first-time buyer.
Home Possible® Home Possible is Freddie Mac’s affordable conventional mortgage for eligible very-low- to moderate-income borrowers.
Potential features include:
Down payment as low as 3% Gifts and grants Employer assistance Permitted secondary financing One-unit primary residence options Conventional mortgage insurance Income, property, education, underwriting, and other program requirements apply.
HomeOne® HomeOne is a Freddie Mac mortgage for qualified first-time homebuyers.
General features include:
Down payment as low as 3% No borrower income limit No geographic restriction Fixed-rate financing One-unit primary residence Homebuyer education when all borrowers are first-time buyers Mortgage insurance for higher loan-to-value transactions Conventional Mortgage Insurance A conventional borrower who makes a down payment below 20% commonly pays private mortgage insurance (PMI) .
PMI:
Protects the lender, not the homeowner Adds to the monthly or upfront mortgage cost Varies according to credit, down payment, property, and coverage May be canceled when applicable legal, investor, equity, and payment-history requirements are met Conventional mortgage insurance may be less expensive than FHA mortgage insurance for some borrowers with stronger credit, but the result depends on the complete loan structure.
2. FHA Loans for First-Time Buyers FHA loans are issued by participating private lenders and insured by the Federal Housing Administration. FHA is not restricted to first-time homebuyers.
HUD states that eligible FHA purchase transactions may require a down payment as low as 3.5%. FHA financing may also allow more flexible credit qualification than many conventional mortgages.
FHA may be worth considering when a buyer:
Has limited down payment savings Needs a more flexible credit review Has a higher debt-to-income ratio Plans to use eligible gift funds Wants to combine the mortgage with permitted assistance Is purchasing an eligible primary residence FHA Mortgage Insurance FHA loans generally require:
An upfront mortgage insurance premium An annual mortgage insurance premium, typically collected monthly FHA mortgage insurance is required regardless of whether the borrower is a first-time buyer. The duration and cost depend on the transaction and current FHA requirements.
Review Loan Factory’s complete guide to FHA loan requirements before choosing FHA based only on the down payment.
FHA Program Disclosure: The 3.5% down payment is a general FHA program feature, not a personalized mortgage offer. Eligibility, rates, APRs, payments, mortgage insurance, fees, loan limits, property standards, and cash to close depend on borrower qualifications, property details, underwriting, and lender guidelines.
3. VA Loans for Eligible First-Time Buyers A VA-backed purchase loan may be one of the strongest options for an eligible Veteran, active-duty Servicemember, qualifying National Guard or Reserve member, or eligible surviving spouse.
VA states that an eligible borrower may purchase without a down payment when the sales price does not exceed the appraised value.
VA-backed purchase loans may also offer:
No monthly private mortgage insurance Limited allowable closing costs Competitive mortgage terms No prepayment penalty Reusable entitlement, subject to VA rules A VA funding fee may apply unless the borrower qualifies for an exemption.
VA is not a first-time buyer-only program. An eligible borrower may use the benefit for a first home or again in a later transaction, depending on entitlement and current VA requirements.
Review Loan Factory’s VA home loan guide when military eligibility may apply.
VA Program Disclosure: No-down-payment financing depends on entitlement, appraisal, sales price, lender underwriting, credit, income, occupancy, and property eligibility. Closing costs and a funding fee may still apply.
4. USDA Loans for Eligible Areas The USDA Single Family Housing Guaranteed Loan Program may provide 100% financing for eligible low- and moderate-income households purchasing a qualifying primary residence in an eligible rural area.
USDA states that applicants generally must:
Meet household-income eligibility Purchase in an eligible rural area Occupy the home as a primary residence Meet citizenship or qualifying residency requirements Satisfy lender and USDA underwriting Use an approved lender Household income generally cannot exceed 115% of the applicable median household income. USDA guaranteed mortgages are generally offered as 30-year fixed-rate loans.
USDA may be useful for buyers in small towns, outer suburban communities, and rural areas. An address does not have to be a farm to qualify.
USDA financing includes an upfront guarantee fee and an annual fee. A zero-down-payment structure therefore does not mean the mortgage has no upfront or ongoing costs.
Review Loan Factory’s USDA home loan guide before assuming a property is eligible based only on its appearance or mailing address.
5. State and Local First-Time Buyer Programs State housing finance agencies, cities, counties, housing authorities, and nonprofit organizations may offer mortgage or assistance programs for eligible first-time buyers.
Programs may provide:
Down payment assistance Closing-cost assistance Below-market or subsidized mortgage structures Mortgage credit certificates Forgivable second mortgages Deferred-payment loans Fully repayable second mortgages Assistance for public-service employees Benefits for targeted neighborhoods Some buyers may also qualify for closing cost assistance programs that help cover eligible upfront expenses. Availability, repayment terms, and qualifying costs depend on the specific program.
Many state and local programs focus on low- or moderate-income buyers, although some serve repeat buyers or designated occupations.
Down Payment Assistance Is Not Always a Grant Assistance may require repayment after:
Selling the home Refinancing Moving out Converting the property into a rental Paying off the first mortgage Leaving an eligible employer Failing to satisfy an occupancy period Review the full promissory note, lien terms, forgiveness schedule, and repayment conditions before using assistance.
Loan Factory’s guide to state and local down payment assistance programs explains the common assistance structures.
6. Special Mortgage and Homebuyer Programs A first-time buyer may also qualify for a program based on something other than first-time ownership.
Examples include:
Good Neighbor Next Door Employer-assisted housing Tribal home loan programs Housing Choice Voucher homeownership Professional mortgage programs Community land trusts Special Purpose Credit Programs Local redevelopment initiatives The CFPB notes that special programs may serve low- or moderate-income borrowers, public-service workers, or buyers purchasing in targeted communities.
A program should be evaluated based on its actual benefit—not simply its name.
What Type of Loan Is Best for a First-Time Home Buyer? There is no universally best loan for a first-time homebuyer.
The most suitable loan is the one that fits the borrower’s eligibility, monthly budget, upfront funds, property, and long-term plans.
Buyer profile
Options to investigate first
Strong credit and stable income Conventional financing Needs a 3% conventional down payment Standard 97%, HomeReady, Home Possible, or HomeOne Limited savings or more flexible credit needs FHA Eligible Veteran or Servicemember VA Buying an eligible rural property USDA Needs help with upfront funds State, local, employer, or nonprofit assistance Meets affordable-program income limits HomeReady, Home Possible, or HFA options Income exceeds affordable-program limits Standard conventional, HomeOne, FHA, VA, or USDA Buying a higher-priced property Conventional high-balance or jumbo financing Purchasing a home needing renovations Eligible conventional or government renovation financing
This table is a starting point, not an eligibility determination.
The CFPB recommends asking lenders to provide multiple loan scenarios when more than one loan type may fit, because the down payment, mortgage insurance, interest, and total cost can differ significantly.
Benefits of First-Time Home Buyer Loans The benefits of first time home buyer loans depend on the specific program. First-time status does not create one automatic package of advantages.
Potential benefits may include:
Lower Down Payment Options Certain conventional loans may allow 3% down, while FHA may allow 3.5%. Eligible VA and USDA borrowers may qualify for no-down-payment financing.
Access to Assistance Programs Some state and local programs give priority to first-time buyers or provide down payment and closing-cost assistance.
Flexible Sources of Funds Depending on the mortgage, eligible sources may include:
Personal savings Gift funds Grants Employer assistance Forgivable loans Deferred second mortgages Community Seconds or Affordable Seconds Affordable Conventional Options HomeReady and Home Possible may provide low-down-payment financing with affordable mortgage insurance features for eligible borrowers. HomeOne and standard 97% financing may serve qualified first-time buyers who do not fit income-limited programs.
Homebuyer Education and Counseling Some programs require education or counseling. This can help buyers understand budgeting, mortgage costs, maintenance, closing, and the responsibilities of homeownership.
Review whether a first-time homebuyer course applies to the selected program.
Ability to Become a First-Time Buyer Again Some programs use a three-year ownership lookback. A buyer who owned a home previously may therefore qualify again after meeting the applicable definition.
First-Time Home Buyer Advantages That Are Not Automatic First-time buyers should not assume that their status automatically provides:
A reduced interest rate A government grant No closing costs No mortgage insurance Guaranteed approval A higher loan amount Forgiveness of mortgage debt Free down payment funds A tax credit A special home price These benefits exist only when a specific program provides them and the buyer meets all requirements.
For example:
FHA permits low down payments, but requires mortgage insurance. VA may provide no-down-payment financing, but military eligibility and a funding fee may apply. USDA may provide 100% financing, but income and property restrictions apply. Assistance may reduce upfront costs, but it may create a second mortgage. Conventional 3% financing may require PMI and stronger credit than FHA. The real first time home buyer advantages come from having more programs to compare—not from receiving every advertised perk.
First-Time Buyer Perks vs. Long-Term Cost A benefit that reduces upfront cash may increase costs elsewhere.
Possible tradeoffs include:
Potential perk
Possible tradeoff
Lower down payment Larger mortgage balance No monthly PMI Different rate, fee, or guarantee structure Down payment assistance Second lien or repayment requirement Lender credit Higher interest rate Discount points More cash required at closing Adjustable-rate mortgage Payment may change after the initial period Longer loan term Lower payment but more interest over time Shorter loan term Less total interest but higher monthly payment
A first-time buyer should compare the entire loan—not only the feature used in the advertisement.
Fixed-Rate vs. Adjustable-Rate Mortgages After choosing a loan program, the buyer may need to choose between a fixed and adjustable interest-rate structure.
Fixed-Rate Mortgage With a fixed-rate mortgage, the principal-and-interest payment is based on an interest rate that does not change during the loan term.
Property taxes, homeowners insurance, mortgage insurance, or HOA dues may still change.
A fixed-rate mortgage may appeal to buyers who:
Want predictable principal and interest Plan to own the home for several years Prefer protection from future rate increases Want a simpler budget Adjustable-Rate Mortgage An adjustable-rate mortgage, or ARM, has an initial rate for a stated period and may adjust afterward according to the loan’s index, margin, and rate caps.
An ARM may be worth reviewing when the buyer:
Understands the adjustment terms Expects to move or refinance before the initial period ends Can afford the possible higher payment Receives a meaningful initial pricing advantage The CFPB recommends reviewing the worst-case payment scenario and adjustment limits before selecting an ARM.
15-Year vs. 30-Year Mortgage The loan term is separate from the loan program.
A 30-year mortgage generally has:
Lower monthly principal and interest More time to repay the loan More total interest when held for the full term A 15-year mortgage generally has:
Higher monthly principal and interest Faster equity growth Less total interest when held for the full term Often a different interest rate The CFPB notes that shorter terms generally reduce total borrowing cost but require a higher monthly payment.
A first-time buyer should select a term based on a sustainable budget rather than focusing only on total interest.
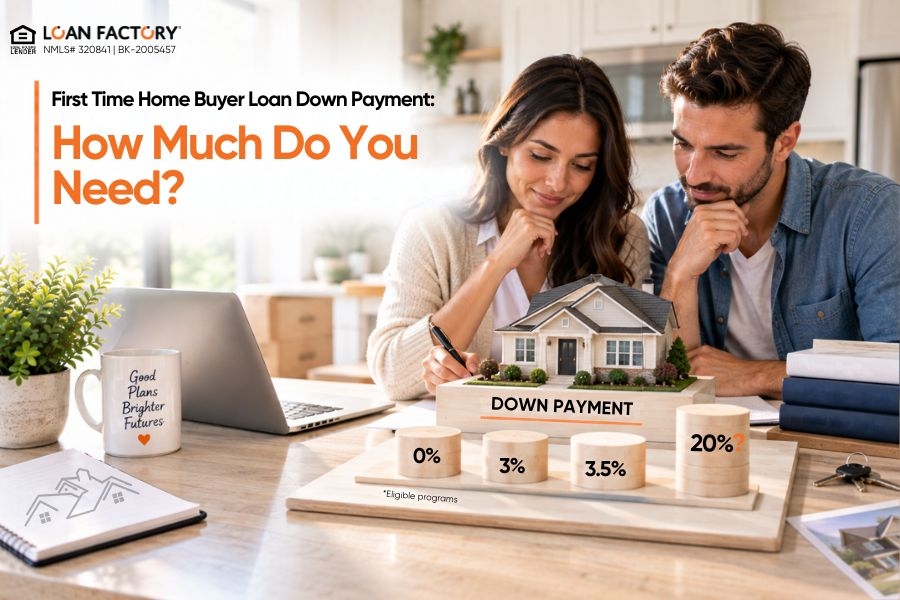
How Down Payment Changes the Loan Options The down payment can affect:
Available mortgage programs Interest rate and loan pricing Mortgage insurance Monthly payment Initial equity Cash remaining after closing Approval strength Risk if property values decline The CFPB explains that conventional financing may be available with as little as 3% down and FHA with 3.5%, while low-down-payment loans can increase mortgage insurance or long-term costs.
Use the Loan Factory mortgage calculator to compare estimated payments at different down payment amounts.
A calculator provides an estimate and is not an approval or official Loan Estimate.
Mortgage Insurance by Loan Type Mortgage insurance should be included when comparing options.
Loan type
Common insurance or guarantee structure
Conventional PMI commonly applies when the down payment is below 20% FHA Upfront and annual mortgage insurance generally apply VA No monthly PMI; funding fee may apply USDA Upfront guarantee fee and annual fee apply State or local program Depends on the first mortgage and assistance structure
Mortgage insurance reduces the lender’s risk but increases the borrower’s cost. It does not protect the borrower from foreclosure or missed payments.
Credit Requirements for First-Time Buyers There is no single credit score required for every first-time buyer loan.
The lender may evaluate:
Credit scores Payment history Collections or charge-offs Credit utilization Recent inquiries Bankruptcy or foreclosure history Housing payment history Debt-to-income ratio Cash reserves Automated underwriting findings A borrower with stronger credit may receive more favorable conventional pricing or lower PMI. A borrower whose credit does not fit conventional guidelines may find FHA more flexible.
Credit score alone does not determine approval. Income, debts, assets, property, occupancy, and the selected program also matter.
Income and Debt Requirements First-time buyer status does not replace the lender’s requirement to verify the borrower’s ability to repay the mortgage.
The lender may review:
Salary or hourly wages Overtime and bonuses Commission income Self-employment income Rental income Retirement or benefit income Student loans Auto loans Credit cards Personal loans Support obligations Proposed housing expense The debt-to-income ratio compares qualifying monthly income with recurring monthly debt obligations and helps lenders evaluate mortgage affordability.
A buyer should set a personal budget that includes more than the mortgage payment:
Property taxes Homeowners insurance Mortgage insurance HOA dues Utilities Repairs Maintenance Emergency savings Documents First-Time Buyers May Need A mortgage application commonly requires:
Identification Driver’s license or passport Social Security number Residency documentation when applicable Current and prior addresses Income and Employment Recent paystubs W-2 forms Tax returns when required Verification of employment Employment contract Self-employment records Assets and Down Payment Bank statements Investment statements Retirement statements Gift documentation Assistance approval Earnest-money records Large-deposit documentation Debts Student loan statements Auto loans Credit card obligations Existing mortgage information Personal loan records Property and Transaction Purchase agreement Property address Homeowners insurance HOA or condominium documents Assistance-program forms Loan Factory’s first-time homebuyer requirements and document checklist explains the records commonly requested.
How to Choose a Mortgage as a First-Time Buyer The strongest mortgage option depends on the entire borrower and property profile.
Step 1: Establish a Complete Housing Budget Include:
Principal and interest Property taxes Homeowners insurance Mortgage insurance HOA dues Utilities Maintenance Repairs Emergency savings Do not use only the maximum loan amount for which a lender may approve you.
Step 2: Review Credit, Income, Debts and Savings Identify:
Credit issues requiring attention Income that can be documented Monthly obligations Available down payment funds Funds needed after closing Step 3: Check Special Eligibility Determine whether you may qualify through:
Military service Rural property location Household income First-time buyer status Employer assistance Public-service occupation State or local programs Step 4: Compare Several Loan Types Ask for estimates under applicable:
Conventional FHA VA USDA Housing finance agency Down payment assistance options Step 5: Get Preapproved Before Serious House Hunting A documented mortgage preapproval may help identify:
Which program may fit Estimated borrowing range Required documents Down payment and cash to close Credit or income issues Property restrictions Preapproval is not final approval.
Step 6: Compare Official Loan Estimates After identifying a property, compare official Loan Estimates using consistent transaction details.
The CFPB recommends comparing:
Loan amount Interest rate Principal-and-interest payment Mortgage insurance Origination charges Points Lender credits APR Cash to close Five-year borrowing cost You can compare mortgage options based on your credit, income, debts, savings, property, and eligibility.
Common First-Time Buyer Loan Mistakes Assuming FHA Is the Only First-Time Buyer Loan FHA is popular among first-time buyers, but conventional, VA, USDA, and assistance-supported options may also be available.
Choosing the Loan With the Smallest Down Payment A smaller down payment may create a larger mortgage balance, higher payment, or additional mortgage insurance.
Looking Only at the Interest Rate Compare APR, points, lender credits, mortgage insurance, cash to close, and expected ownership period.
Treating Assistance as Free Money Some assistance must be repaid after a sale, refinance, move, or employment change.
Ignoring Property Restrictions USDA, VA, FHA, condominium, manufactured-home, and assistance programs may have specific property requirements.
Using All Available Savings at Closing Preserve money for moving, repairs, insurance deductibles, and unexpected expenses.
Applying for New Credit Before Closing A new auto loan, credit card, or personal loan may affect credit, debts, and final approval.
Assuming Preapproval Guarantees the Loan The lender may reverify income, employment, assets, credit, debts, property, appraisal, title, and insurance.
Review the Loan Factory loan process to understand the steps from application through underwriting and closing.
How Loan Factory Helps First-Time Buyers Compare Mortgage Options Loan Factory is a technology-powered mortgage platform helping borrowers compare mortgage options through a broad wholesale lender network.
A licensed Loan Officer can help first-time buyers:
Compare conventional, FHA, VA, and USDA financing Review 3% down conventional options Identify available down payment assistance Evaluate mortgage insurance Review gift funds, seller credits, and lender credits Estimate down payment separately from cash to close Review income, debts, and credit Compare fixed and adjustable-rate options Compare 15-year and 30-year terms Review rate, APR, fees, payment, and five-year borrowing cost Prepare documents before making an offer TERA supports online applications, secure document uploads, e-signing, communication, and loan-status tracking. Technology can support the mortgage process but does not guarantee eligibility, approval, closing, or funding.
Learn more about Loan Factory and its technology-supported mortgage process.
Choosing Among Mortgage Options for First Time Buyers Mortgage options for first time buyers include conventional 3% down programs, FHA, VA, USDA, housing finance agency loans, and down payment assistance.
The right loan is not automatically the one with the lowest down payment or the most recognizable program name. Compare qualification, mortgage insurance, monthly payment, cash to close, property restrictions, assistance repayment, rate, APR, and long-term cost.
When you are ready, apply for a mortgage online or call or text (660) 333-3333 to discuss your mortgage options with a Loan Factory mortgage professional.
Experience Note The loan comparisons, borrower profiles, cost tradeoffs, document lists, and selection steps in this article are educational illustrations based on common first-time homebuyer mortgage considerations.
They do not represent a specific Loan Factory borrower, rate, APR, payment, Loan Estimate, preapproval, approval, closing, or funded transaction.
Sources About the Author Loan Factory Mortgage Education Team
Loan Factory is a technology-powered mortgage platform helping borrowers compare mortgage options through a broad wholesale lender network.
The Loan Factory Mortgage Education Team helps first-time buyers understand conventional, FHA, VA, USDA, down payment assistance, mortgage insurance, documentation, and the home-purchase process.
Disclaimer This content is for educational and informational purposes only and is not financial, tax, legal, credit, accounting, real estate, insurance, investment, or housing-counseling advice. It is not a commitment to lend or a guarantee of preapproval, approval, rates, APRs, payments, benefits, assistance, loan amount, property value, closing, or funding.
Mortgage programs, first-time buyer definitions, down payment requirements, assistance funding, rates, fees, credits, mortgage insurance, income limits, documentation, loan limits, property requirements, and eligibility may change and vary by borrower, agency, lender, property, occupancy, location, underwriting, investor, and program administrator.
Loan Factory is a private mortgage company and is not affiliated with or acting on behalf of HUD, FHA, VA, USDA, Fannie Mae, Freddie Mac, FHFA, CFPB, a state housing agency, or another government entity.
Frequently Asked Questions