If you want to know how to become a mortgage loan officer in Arizona , the process starts with NMLS education, the SAFE exam, background review, and sponsorship from a licensed mortgage company.
But getting licensed is only the first step.
Arizona is a relationship-driven mortgage market. A new Mortgage Loan Officer may work with first-time buyers, FHA borrowers, VA borrowers, relocation buyers, investors, retirees, self-employed borrowers, and new construction clients across Phoenix, Tucson, Mesa, Scottsdale, Chandler, Gilbert, Glendale, and surrounding growth areas.
That means your success depends on more than passing the test. You also need the right company, lender access, technology, training, compliance support, and a clear local market strategy.
This guide explains the Arizona licensing path and how to move from license approval to real borrower conversations.
Quick Answer: How Do You Become a Mortgage Loan Officer in Arizona? To become a Mortgage Loan Officer in Arizona, you generally need to:
Create an NMLS account Complete Arizona-required pre-licensing education Pass the SAFE Mortgage Loan Originator Test Complete fingerprints, background check, and credit authorization Apply for your Arizona Mortgage Loan Originator license through NMLS Obtain sponsorship from a licensed mortgage company Complete company onboarding and compliance training Learn real borrower scenarios, lender pricing, documents, and file flow In Arizona, licensing gives you the legal foundation. Sponsorship and training help you become ready to work with actual borrowers.
Mortgage Loan Officer vs MLO in Arizona In many conversations, the terms Mortgage Loan Officer, Mortgage Loan Originator, and MLO are used together.
A Mortgage Loan Officer helps borrowers apply for residential mortgage financing. The licensed role is commonly referred to as a Mortgage Loan Originator, or MLO.
An Arizona Mortgage Loan Officer may help borrowers with:
Home purchase loans Refinance loans FHA loans VA loans Conventional loans Jumbo loans Investment property loans First-time homebuyer questions Mortgage applications Loan option comparisons Document collection Borrower communication A strong Mortgage Loan Officer does more than take an application. They help borrowers understand what may be possible, prepare their file, compare loan options, and move through the mortgage process with clear guidance.
Those exploring the profession can review becoming a Loan Officer for a broader overview of the career, licensing process, and steps involved in entering the mortgage industry.
Arizona Mortgage Loan Officer Licensing Checklist Here is a simple overview of the Arizona path.
Step
What You Need to Do
Why It Matters
1 Create an NMLS account Starts your licensing profile 2 Complete Arizona PE education Satisfies required mortgage law and ethics education 3 Pass the SAFE exam Shows you understand core mortgage rules 4 Complete background items Allows regulator review of eligibility and financial responsibility 5 Apply through NMLS Submits your Arizona license request 6 Get company sponsorship Allows you to originate under a licensed company 7 Complete onboarding Helps you move from licensed to production-ready
The strongest candidates treat this as both a licensing process and a career launch process.
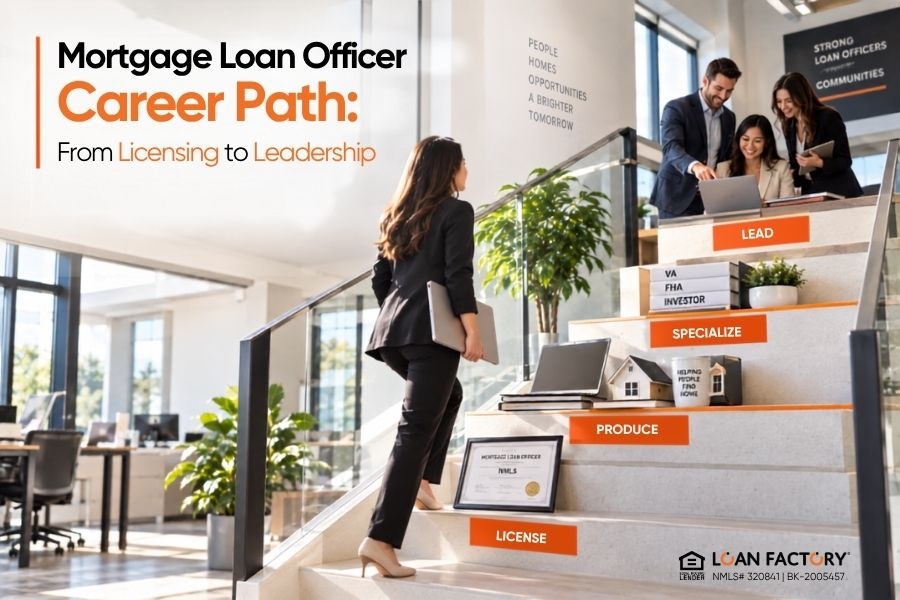
For a broader look beyond Arizona licensing, review the Mortgage Loan Officer career path to understand how an MLO can progress from licensing and early production to more advanced mortgage expertise.
Step 1: Create Your NMLS Account Your first step is creating an account with NMLS, the Nationwide Multistate Licensing System.
Your NMLS profile tracks:
Pre-licensing education SAFE exam results License applications Background check items Credit report authorization Company sponsorship Continuing education Renewal status You will use NMLS throughout your mortgage career, so keep your personal information accurate from the beginning.
Step 2: Complete Arizona Pre-Licensing Education Arizona requires future state-licensed Mortgage Loan Originators to complete NMLS-approved pre-licensing education.
The Arizona education requirement includes federal mortgage education plus Arizona-specific law content.
Education Requirement
Hours
Federal law 3 Ethics, including fraud, consumer protection, and fair lending 3 Nontraditional mortgage lending 2 Electives / undefined education 8 Arizona law 4 Total 20
The Arizona law portion helps future Mortgage Loan Officers understand state-specific mortgage rules and compliance expectations.
All coursework must be completed through an NMLS-approved provider.
Step 3: Pass the SAFE Mortgage Loan Originator Test After completing education, the next major step is passing the SAFE Mortgage Loan Originator Test.
The SAFE exam covers:
Federal mortgage laws Loan origination activities Ethics Consumer protection Mortgage products General mortgage knowledge Uniform state content A passing score is generally 75% or higher.
If you are new to mortgage, do not rely on memorization alone. The SAFE exam tests whether you understand mortgage concepts, consumer protection, fair lending, compliance, and responsible loan origination.
A practical study plan should include:
Mortgage vocabulary review Federal law review Practice questions Ethics and fair lending review Test simulations Review of weak areas Enough time before scheduling the test Loan Factory’s Loan Officer Exam Center can help future Loan Officers understand the licensing path and prepare for the next step.
Step 4: Complete Fingerprints, Background Check, and Credit Review Arizona MLO applicants must complete required background and financial responsibility review items.
This commonly includes:
Fingerprinting Criminal background check authorization Credit report authorization Disclosure explanations when required Review of financial responsibility A past credit issue does not automatically mean you cannot become licensed. However, regulators may review the details and may request explanations depending on the situation.
Be accurate, complete, and transparent throughout the application process.
Step 5: Apply for Your Arizona MLO License After completing education and passing the SAFE exam, you can apply for your Arizona Mortgage Loan Originator license through NMLS.
Your application may include:
Personal information Education records SAFE exam results Fingerprint authorization Background check authorization Credit report authorization Required licensing fees Company sponsorship information when applicable Arizona regulators review the application before approval.
Getting licensed does not automatically mean you can originate loans independently.
Mortgage Loan Officers generally need sponsorship from a licensed mortgage company before originating residential mortgage loans.
This is one of the most important decisions for a new Arizona Mortgage Loan Officer because your sponsoring company affects your:
Training Technology Lender access Compliance supervision Marketing support Processing support Lead opportunities Compensation structure Day-to-day learning experience A company should not only hold your license. It should help you learn how to work real mortgage scenarios.
New Loan Officers should also understand how Loan Officer compensation may be structured and which compensation factors are subject to federal compliance requirements.
Step 7: Complete Company Onboarding and Training After licensing and sponsorship, the next step is learning how to operate within your mortgage company’s systems, procedures, and compliance framework.
Onboarding may include training on:
Loan origination systems Pricing and lender platforms Mortgage applications Document collection Loan programs and guidelines Compliance procedures Borrower communication Processing workflows Marketing tools Company policies This stage helps bridge the gap between obtaining an MLO license and becoming prepared to work with borrowers and real mortgage scenarios.
New Loan Officers should focus on building strong mortgage fundamentals, learning company procedures, and understanding when to ask experienced team members for guidance.
How to Choose Your Arizona Mortgage Niche One way to avoid feeling lost as a new Mortgage Loan Officer is to choose a starting niche.
You do not need to limit yourself forever, but a niche can help you focus your learning, marketing, and referral strategy.
Arizona Borrower Segment
Why It Can Be a Useful Starting Point
First-time buyers Need education, payment clarity, and step-by-step guidance FHA borrowers Common for buyers who need flexible qualifying options VA borrowers Arizona has active military and veteran communities Relocation buyers Many buyers move to Arizona from other states New construction buyers Arizona has active new-home communities Investors Arizona attracts rental-property and investment buyers Self-employed borrowers Need strong income review and lender matching Refinance clients Need rate, payment, term, and cash-flow comparison guidance
A focused niche helps you learn faster because you see similar borrower questions repeatedly.
Where New Arizona Mortgage Loan Officers Can Build Relationships Mortgage is a relationship business. New Loan Officers should start building trust before they expect referrals.
Potential relationship sources include:
Real estate agents Home builders Financial professionals Insurance agents Tax professionals Local business owners Community groups Past coworkers Friends and family Relocation networks Veteran and military communities First-time homebuyer education groups The goal is not to pressure people. The goal is to become known as someone who can explain mortgage options clearly, follow up professionally, and help borrowers understand the process.
What New Arizona Mortgage Loan Officers Should Learn First New Mortgage Loan Officers often try to learn everything at once. That can become overwhelming.
A better approach is to build skills in layers.
Start With Borrower Conversations Learn how to ask clear questions about:
Homebuying timeline Loan purpose Income type Employment status Credit situation Down payment funds Property type Occupancy Monthly payment comfort level Current mortgage situation for refinance clients Then Learn Loan Program Basics Focus first on the most common programs:
Conventional loans FHA loans VA loans Jumbo loans Refinance options Investor property financing basics Then Learn File Flow Understand how a loan moves through:
Application Document collection Pricing Disclosures Processing Underwriting Conditions Approval Closing Then Learn Lender Comparison A good Mortgage Loan Officer should understand how to compare:
Rate APR Fees Lender credits Monthly payment Cash to close Mortgage insurance Program guidelines Underwriting fit This is where technology and lender access become especially valuable.
A mortgage technology platform for Loan Officers can help bring pricing, CRM, applications, marketing, and loan workflow into a more coordinated system.
Arizona-Specific Mortgage Scenarios New LOs May See Arizona has borrower scenarios that can help new Mortgage Loan Officers build practical experience.
Common Arizona scenarios may include:
Buyers relocating from California or other states Retirees purchasing in Arizona Veterans using VA loan options First-time buyers comparing FHA and conventional options Self-employed borrowers with variable income Buyers considering new construction homes Investors purchasing rental properties Borrowers comparing refinance options High-growth suburban market purchases Each scenario teaches different skills. That is why live support and lender access matter for new LOs.
Common Mistakes New Arizona Mortgage Loan Officers Make Mistake 1: Choosing a company only by commission Commission matters, but new Loan Officers often need training, technology, lender access, compliance support, and live scenario guidance even more in the beginning.
Mistake 2: Waiting too long after passing the SAFE exam If you delay sponsorship and onboarding, you can lose momentum. The faster you move into structured training, the faster you begin connecting licensing knowledge with real borrower scenarios.
Mistake 3: Trying to serve every borrower immediately It is better to master common scenarios first, then expand. Start with a niche, learn the questions, and build confidence.
Mistake 4: Paying for too many tools too early Some new LOs pay separately for CRM, pricing tools, websites, texting systems, marketing platforms, and lead services before they have consistent production.
A built-in platform can help reduce unnecessary overhead.
Mistake 5: Ignoring compliance in marketing Mortgage advertising, social media, texting, calling, and borrower communication are regulated. New LOs must follow company approval processes and applicable federal and state rules.
Arizona Continuing Education After Licensing After becoming licensed, Arizona MLOs must complete annual continuing education to maintain an active license.
Arizona continuing education generally includes:
Continuing Education Requirement
Hours
Federal law 3 Ethics 2 Nontraditional mortgage lending 2 Arizona-specific education 1 Total 8
Do not wait until the last minute to complete continuing education. Course providers may need time to report completion to NMLS.
Why Loan Factory Is a Strong Fit for Arizona Mortgage Loan Officers If you want to become a Mortgage Loan Officer in Arizona, choosing the right company can help you move from licensing to real production skills.
Loan Factory supports both newly licensed and experienced Loan Officers with technology, lender access, training, marketing support, underwriting support, and live guidance.
Why Choose Loan Factory Licensed in 48 states Access to Tera technology platform for CRM, LOS, pricing, marketing, and compliance support Access to 240+ wholesale lenders with side-by-side pricing and 1-click locks Training for all levels, including newly licensed Loan Officers Weekly live training and Loan Factory Academy Marketing and underwriting support Live Loan Officer support for real-time loan scenarios No monthly desk fees or junk fees 100% commission minus a flat $595 fee on eligible self-generated loans Commission options available for both 1099 and W2 Loan Officers, depending on production model and company policy In-house processing available at $500 per file Company-generated leads available in 42 states, subject to availability and disclosed lead split terms Free or paid Facebook leads available in select scenarios, subject to availability Mentorship from Thuan Nguyen, one of the top-producing Loan Officers in the U.S. Cash or RSU referral opportunities when referring qualified Loan Officers Loan Officers operate under company supervision and must comply with federal and Arizona regulations, including the SAFE Act, TILA, RESPA, MAP, TCPA, and company advertising approval requirements.
Loan Factory is designed to help new and experienced LOs build real mortgage production skills with the right systems, support, and lender access behind them.
Who Can Join Loan Factory? Loan Factory may be a fit for:
Newly licensed Loan Officers Loan Officers who have closed 2 or more loans in the past 12 months Not licensed yet? Future Loan Officers can explore Loan Factory’s licensing resources, exam preparation tools, and career information as they work toward becoming licensed.
Eligibility is subject to licensing requirements, applicable state regulations, background checks, company requirements, and management approval.
Ready to Become a Mortgage Loan Officer in Arizona? If you are not licensed yet, start by learning the NMLS process, SAFE exam steps, and Arizona licensing path.
Start Here Loan Officer Exam Centerhttps://www.loanfactory.com/loan-officer-exam-center
Already licensed or preparing to choose a mortgage company?
Join the Loan Factory Webinar https://www.loanfactory.com/loan-officer
Ready to join Loan Factory directly?
Register Here https://www.loanfactory.com/register-loan-officer
For questions, call 714-591-8143.
Experience Note This article is based on real mortgage recruiting, licensing, onboarding, and training scenarios reviewed by Loan Factory’s recruiting and education teams working with aspiring, newly licensed, and experienced Mortgage Loan Originators across multiple U.S. markets.
Disclaimer This article is for informational purposes only and does not constitute legal, licensing, regulatory, employment, tax, or financial advice. Licensing requirements, sponsorship rules, compensation structures, training availability, lead availability, and company programs may vary and can change over time. Always verify current licensing requirements with NMLS and the applicable Arizona regulator.
FAQ: How to Become a Mortgage Loan Officer in Arizona