The appraisal to closing timeline can vary by lender, loan type, appraisal result, underwriting status, title review, insurance, and closing conditions. In many mortgage transactions, closing after the appraisal may take about 15 to 30 days, but the actual timeline depends on the file.
The appraisal is only one step in the mortgage process.
After the appraisal, the lender still needs to review the report, confirm the property value supports the loan amount, clear underwriting conditions, issue the Closing Disclosure, and prepare final closing documents.
A smooth appraisal can help the loan move forward.
A low value, required repairs, property eligibility issue, title problem, or missing document can delay closing.
Important note: This article is for informational purposes only and is not a commitment to lend. Appraisal timing, appraisal results, loan approval, closing timelines, rates, APR, fees, terms, and program availability depend on borrower qualifications, property details, appraisal findings, lender guidelines, investor requirements, underwriting approval, and closing conditions.
Key Takeaways The appraisal-to-closing timeline depends on the appraisal result, underwriting review, title, insurance, loan type, and closing conditions. A home appraisal can take days to weeks to complete, depending on the property, market, appraiser availability, and report complexity. After the appraisal is submitted, the lender reviews the appraisal and the underwriter checks whether the property supports the loan amount and loan program requirements. Borrowers are generally entitled to receive a copy of appraisals and written valuations promptly after completion or at least three business days before closing, whichever is earlier. If the appraisal is low or repairs are required, the closing timeline may be extended. Loan Factory can help buyers understand appraisal results, compare mortgage options, and prepare for next steps before closing. What Is the Appraisal to Closing Timeline? The appraisal to closing timeline is the period between the home appraisal review and the final mortgage closing. This stage usually includes appraisal report submission, lender review, underwriting, condition clearing, Closing Disclosure delivery, final document preparation, signing, funding, and recording.
The appraisal and closing process typically includes the following steps:
Step
What Happens
Appraisal ordered Lender or appraisal management company orders the appraisal Appraiser visits property Appraiser observes the home and gathers property details Appraisal report completed Appraiser submits value report to lender Lender reviews appraisal Underwriter or review team checks value, property, and report quality Conditions cleared Borrower, seller, title, insurance, or appraiser may need to provide items Clear to close Underwriter confirms major conditions are satisfied Closing Disclosure issued Borrower receives final loan terms and closing cost disclosure Final documents prepared Closing package is sent to title/escrow/settlement agent Closing day Borrower signs final documents Funding and recording Loan funds and title transfer is completed based on state process
The appraisal itself does not close the loan.
It gives the lender important property information needed to move the file toward final approval.
How Long Does a Home Appraisal Take? A home appraisal can take anywhere from a few days to a few weeks from order to completion. The property visit itself may be short, but scheduling, market research, comparable sales analysis, report writing, and lender review can take longer.
Rocket Mortgage explains that the Closing Disclosure is a standardized five-page document showing final loan terms, projected monthly payment, APR, and closing costs. For most mortgages, the lender must ensure that borrowers receive the Closing Disclosure at least three business days before loan consummation (typically when the borrower signs the loan documents).
The appraisal timeline may include:
1. Appraisal Order After the purchase agreement is signed and the loan is in process, the lender orders the appraisal.
In many cases, the appraiser or appraisal management company contacts the listing side to schedule the property visit.
2. Property Visit The appraiser may visit the home to observe:
Interior condition Exterior condition Room count Gross living area Property features Upgrades Repairs Safety or habitability concerns Neighborhood and site conditions 3. Market Research After the visit, the appraiser researches the local market and comparable sales.
Fannie Mae requires appraisers to analyze comparable sales and explain why specific comparables were used in the appraisal report.
4. Report Completion The appraiser completes the appraisal report and sends it to the lender.
The lender then reviews the report before the file can move forward.
The property visit may be quick, but the full appraisal process includes much more than the visit.
What Happens After the Appraisal Is Submitted? After the appraisal is submitted, the lender reviews the report to confirm that the property value, condition, and eligibility support the requested loan. The underwriter may also check whether the appraisal meets loan program and investor requirements.
This review may include:
Appraised value Contract price Loan amount Loan-to-value ratio Property condition Comparable sales Marketability Required repairs Property eligibility Appraisal report completeness Loan program requirements Fannie Mae’s appraisal review guidance says appraisal report review includes transaction details, property and appraisal eligibility analysis, and appraisal report assessment requirements.
The appraised value also affects the loan-to-value ratio , which compares the loan amount with the property value.
The appraisal result may lead to one of three common outcomes:
Appraisal Result
What It May Mean
Value supports purchase price Loan may continue through underwriting Value is higher than purchase price Loan may continue if other conditions are met Value is lower than purchase price Buyer, seller, and lender may need to review options Repairs are required Repairs and reinspection may be needed before closing Report has issues Appraisal correction, review, or clarification may be required
A clean appraisal can help the loan move forward.
An appraisal issue can create additional steps.
Appraisal to Closing Timeline: Step-by-Step A typical appraisal to closing timeline includes lender review, underwriting, condition clearing, Closing Disclosure delivery, final approval, signing, funding, and recording. Each step can move quickly or slow down depending on the file.
Step 1: Appraisal Report Is Delivered to the Lender The first step after the appraisal is report delivery.
The report usually includes:
Subject property information Interior and exterior photos Comparable sales Market analysis Property condition notes Adjustments Appraiser’s opinion of value Borrowers are generally entitled to receive a copy of appraisals and other written valuations used for a first-lien home loan promptly upon completion or at least three business days before closing, whichever is earlier.
Review the report carefully when you receive it.
Look for:
Correct property address Accurate bedroom and bathroom count Correct square footage Correct property type Correct sales contract details Major missing improvements Obvious factual errors Step 2: Lender Reviews the Appraisal The lender reviews the appraisal to confirm that the value supports the loan.
If the appraisal is acceptable, the file can continue.
If there are concerns, the lender may ask for:
Appraisal correction Additional comparable sales explanation Reconsideration of value request Repair completion Final inspection Underwriting review Loan structure changes Step 3: Underwriting Continues The mortgage underwriter reviews both the borrower and the property.
Borrower review may include:
Income Assets Credit Monthly debts Employment Down payment Cash to close Loan program eligibility Property review may include:
Appraised value Property type Occupancy Title Insurance Condition Loan-program requirements An appraisal can be complete while other underwriting conditions are still pending.
That is why the appraisal result does not automatically mean the loan is ready to close.
For a closer look at the remaining review stages, see our guide to the mortgage underwriting process timeline .
Step 4: Conditions Are Cleared Conditions are remaining items that must be satisfied before final approval.
Common conditions may include:
Updated bank statement Pay stub Verification of employment Homeowners insurance Title documents Appraisal correction Repair confirmation Gift letter Source of funds Explanation letter Updated credit or debt information Final purchase contract addendum The faster required conditions are cleared, the faster the file can move toward closing.
Step 5: Clear to Close “Clear to close” usually means the underwriter has confirmed the file is ready for final loan documents, subject to final closing steps.
At this stage, the lender may prepare the closing package.
However, buyers should still avoid major financial changes.
Do not:
Open new credit Finance a car Make large undocumented deposits Change jobs without guidance Move money without keeping records Miss payments Increase credit card balances A final verification can still occur before closing. Unlike mortgage pre-approval , clear to close indicates that required underwriting conditions have generally been accepted, although final closing steps remain.
Step 6: Closing Disclosure Is Issued Before closing, the borrower receives the Closing Disclosure.
Rocket Mortgage explains that the Closing Disclosure is a standardized five-page document showing final loan terms, projected monthly payment, APR, and closing costs. For most mortgages, borrowers must receive it at least three business days before their scheduled closing.
Review the Closing Disclosure carefully.
Compare it with your earlier Loan Estimate and ask about:
Final cash to close Interest rate APR Monthly payment Taxes and insurance Lender credits Closing costs Prepaid items Escrow setup Any unexpected changes Step 7: Final Signing, Funding, and Recording At closing, the borrower signs final loan documents.
Depending on the state and transaction type, the final steps may include:
Signing loan documents Wiring or bringing certified funds Lender funding Title/escrow disbursement Deed recording Seller payoff Buyer receives keys based on local practice and contract terms Closing is complete only after the required signing, funding, and recording steps are finished.
How Long After the Appraisal Can You Close? How long after the appraisal you can close depends on whether the appraisal is accepted, whether underwriting is complete, whether title and insurance are ready, and whether the Closing Disclosure timing requirement has been met.
In many cases, buyers may close within a couple of weeks after a clean appraisal if the file is otherwise ready.
However, closing may take longer if:
Appraisal value is low Repairs are required Appraisal correction is needed Underwriting conditions are still pending Title issues appear Insurance is not finalized Closing Disclosure timing has not started Buyer has missing documents Seller has unresolved repairs Loan program requires additional review Rocket Mortgage notes that closing after appraisal is typically affected by appraisal results, loan type, and lender process, with a common expectation of 15 to 30 days after the appraisal is complete.
A clean appraisal helps, but the rest of the loan file must also be ready.
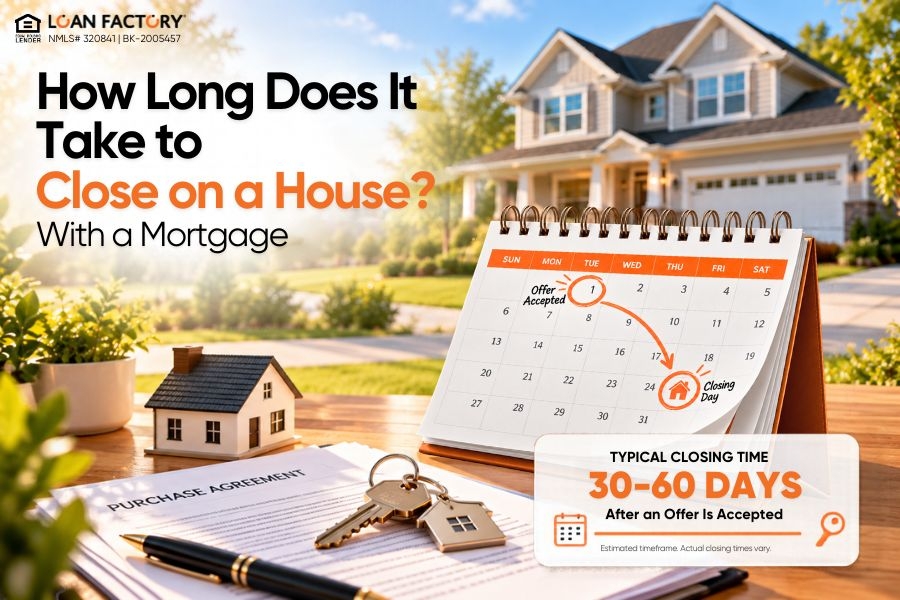
To understand the full homebuying timeline beyond the appraisal, read our guide on how long it takes to close on a house with a mortgage .
How Long Does an Appraisal Last? How long an appraisal lasts depends on the loan program, lender guidelines, property changes, market conditions, and whether an appraisal update is required. Appraisal validity is not the same for every mortgage type.
For conventional loans delivered to Fannie Mae, the appraisal report generally must meet age requirements. Fannie Mae states that if the effective date of the original appraisal report is more than four months from the date of the note and mortgage, an appraisal update is required; if it is more than 12 months, a new appraisal report is required.
For FHA, HUD announced that for most Title II forward and HECM originations, FHA extended the initial appraisal validity period from 120 days to 180 days and extended appraisal update validity from 240 days to one year.
For VA, VA guidance states that for existing housing, the appraisal is valid for six months from the date of the Notice of Value, and proposed construction is valid for 12 months from the date of the Notice of Value.
Simple Appraisal Validity Snapshot Loan Type
General Appraisal Timing Rule
Conventional / Fannie Mae Appraisal update may be needed if older than four months; new appraisal required if older than 12 months FHA Most initial appraisals valid for 180 days under FHA’s revised guidance VA Existing housing appraisal generally valid for six months from NOV date USDA Validity depends on USDA/lender requirements and file specifics Jumbo Depends on investor and lender guidelines
Program rules can change.
Always confirm appraisal validity with the lender handling your loan.
What Can Delay Closing After Appraisal? Closing after appraisal can be delayed by low appraised value, required repairs, appraisal corrections, title issues, insurance problems, missing borrower documents, underwriting conditions, or loan-program property requirements.
Low Appraised Value A low appraisal means the appraised value is below the purchase price.
Possible options may include:
Renegotiate purchase price Buyer brings additional funds if allowed and affordable Seller gives concessions if allowed Request reconsideration of value through the lender Adjust loan structure Cancel under contract terms, if available A low appraisal can affect loan-to-value ratio and cash needed to close.
Required Repairs Some appraisals include repair conditions.
Common repair issues may include:
Peeling paint Broken windows Missing handrails Roof concerns Exposed wiring Safety hazards Water damage Incomplete construction Utility problems If repairs are required, the appraiser may need to reinspect the property before closing.
For borrowers using FHA loans , property condition and applicable FHA appraisal requirements may affect which repairs must be completed before closing.
Rocket Mortgage notes that if an appraiser flags safety hazards during an FHA appraisal, repairs may be required and the appraiser may need to return to verify completion, which can extend the timeline.
Appraisal Corrections or Review The lender may ask the appraiser for corrections or clarification.
This may happen if:
Comparable sales need explanation Property details appear inconsistent Photos are missing Contract details are incorrect Adjustments need clarification The appraisal has data errors Title or Insurance Issues Even if the appraisal is clean, title and insurance must still be ready.
Delays may happen if:
Title has unresolved liens Seller payoff information is missing Homeowners insurance is not finalized Flood insurance is required HOA documents are delayed Closing agent needs corrections Borrower Documentation Issues Borrowers may delay closing if they do not provide requested documents quickly.
Examples include:
Updated pay stub Updated bank statement Gift letter Source of funds documentation Explanation letter Insurance binder Final cash-to-close verification The appraisal is important, but closing depends on the full file.
First-time buyers can use our first-time homebuyer document checklist to organize commonly requested paperwork and reduce avoidable documentation delays.
What Happens If the Appraisal Comes in Low? If the appraisal comes in low, the lender may base the loan amount on the lower appraised value instead of the contract price. This can create an appraisal gap that must be resolved before closing.
Common options may include:
Option
How It May Help
Renegotiate price Seller reduces price closer to appraised value Increase down payment Buyer covers some or all of the gap, if allowed and affordable Seller credit or concession May help with costs, subject to guidelines Reconsideration of value Lender submits factual support for appraisal review Change loan structure May help if guidelines allow Cancel contract May be possible if appraisal contingency applies
A reconsideration of value should be based on facts.
Useful support may include:
Missing comparable sales Incorrect square footage Missing upgrades Incorrect room count Incorrect property condition Public record errors Stronger market data Federal agencies have issued guidance on reconsideration of value processes to help institutions handle valuation-related questions, including potential errors or concerns.
What Happens If the Appraisal Requires Repairs? If the appraisal requires repairs, the lender may require proof that repairs are completed before final loan approval or closing. The process depends on the loan type, repair issue, property condition, and lender guidelines.
Possible repair steps include:
Seller completes repairs Contractor provides invoice Photos are submitted if accepted Appraiser completes final inspection Lender reviews repair evidence Underwriter clears condition Closing timeline is updated Some repairs must be completed before closing.
Other repairs may be handled differently if the loan program allows.
Do not assume repair escrow or post-closing repair options are available.
Ask your loan advisor early.
Appraisal to Closing Timeline for Different Loan Types The appraisal to closing timeline may vary by loan type because Conventional, FHA, VA, USDA, Jumbo, and specialty loans may have different property review and underwriting requirements.
Loan Type
What May Affect Timeline
Conventional Appraisal review, property eligibility, value support, underwriting conditions FHA Property condition, repair requirements, safety issues, FHA appraisal rules VA VA appraisal, Notice of Value, Minimum Property Requirements, Tidewater or value review if applicable USDA Property eligibility, location eligibility, underwriting, agency-related review Jumbo Investor overlays, larger loan review, appraisal depth, reserve requirements Renovation loans Scope of work, contractor documents, after-improved value, draw process
A loan with a clean appraisal and complete documents can move faster.
A loan with property repairs, missing documentation, or appraisal questions can take longer.
How to Help Keep the Closing Timeline Moving You cannot control every part of the appraisal process, but you can reduce avoidable delays by staying organized, responding quickly, and avoiding financial changes before closing.
Buyer Checklist After Appraisal Review the appraisal report when received Check basic property details for accuracy Respond quickly to lender document requests Keep pay stubs and bank statements updated Avoid new credit or new debts Do not change jobs without lender guidance Keep funds for closing documented Confirm homeowners insurance early Ask about title or HOA issues Review Closing Disclosure immediately Ask questions before signing day Seller Checklist After Appraisal Complete required repairs quickly Provide access for reinspection if needed Send receipts or invoices when requested Respond to title requests Keep utilities on if needed Communicate with listing agent and buyer’s team Agent Checklist After Appraisal Watch for low value or repair conditions Help coordinate access if reinspection is needed Provide factual comparable sale support if value review is appropriate Help negotiate if appraisal gap appears Track contract deadlines Fast communication can protect the timeline when the appraisal creates questions.
Case Study: Clean Appraisal vs. Delayed Appraisal Here is a hypothetical example of how appraisal results can affect closing.
Hypothetical example only: This is for informational purposes only and not a commitment to lend. Appraisal results, loan approval, closing timeline, rates, APR, fees, terms, and conditions depend on borrower qualifications, property details, lender guidelines, appraisal findings, underwriting, title, insurance, and applicable program rules.
Scenario A: Clean Appraisal The appraiser visits the property, completes the report, and the value supports the contract price.
The lender reviews the appraisal, clears property conditions, and underwriting continues.
The borrower provides updated documents quickly.
The file moves to clear to close and Closing Disclosure.
Closing stays on track.
Scenario B: Delayed Appraisal The appraiser notes peeling paint, a broken handrail, and a value below the contract price.
The seller completes repairs.
The appraiser returns for reinspection.
The buyer and seller negotiate the value gap.
The lender reviews the updated appraisal condition.
Closing is delayed.
Loan Factory Experience Note : In real purchase files, appraisal delays often happen because of low value, repair requirements, missing documents, or slow communication. The strongest files usually have clear property access, complete borrower documents, early insurance setup, and quick responses to underwriting conditions.
Appraisal to Closing Timeline Checklist Use this checklist to understand what should happen before closing.
Item
Status to Confirm
Appraisal ordered Ordered by lender or AMC Appraiser appointment Scheduled and completed Appraisal report Delivered to lender Borrower copy Received and reviewed Value accepted Appraisal supports loan structure Repairs Completed and cleared if required Underwriting conditions Submitted and reviewed Title Cleared or in final review Homeowners insurance Bound and accepted Closing Disclosure Received and reviewed Final approval Clear to close issued Closing appointment Scheduled Funds to close Verified and ready Signing Completed Funding/recording Completed according to local process
This checklist does not guarantee closing.
It helps buyers see what remains after the appraisal.
Why Choose Loan Factory Loan Factory helps homebuyers compare mortgage options from 240+ wholesale lenders using technology designed to make the home loan process clearer, faster, and more transparent.
If you are waiting on an appraisal or trying to understand the appraisal to closing timeline, Loan Factory can help explain how appraisal results may affect underwriting, cash to close, loan approval, and final closing steps.
What Loan Factory Offers Homebuyers Access to 240+ wholesale lenders Transparent side-by-side mortgage options to review rate, APR, payment, fees, and cash-to-close TERA technology platform to support pricing, loan comparison, document flow, and loan review Local loan advisor support to help explain appraisal results and closing conditions No application fee to start reviewing your options Guidance for first-time buyers, repeat buyers, FHA, VA, Conventional, USDA, Jumbo, and other available programs depending on eligibility Support before you shop, make an offer, respond to appraisal results, or move toward closing A clean appraisal can help the loan move forward.
Loan Factory helps you understand the next steps after the appraisal.
Waiting on an appraisal or preparing to close?
Estimate your payment: Loan Factory Mortgage Calculator LoanFactory.com/quote LoanFactory.com/apply Loan Factory Mortgage Rate Alert
Author Box Written by: Loan Factory Mortgage Education Team
Loan Factory is a technology-powered mortgage platform helping homebuyers compare mortgage options from 240+ wholesale lenders. Our mortgage education content is designed to help buyers understand appraisals, underwriting, closing timelines, mortgage approval, affordability, and the home loan process before applying.
Compliance Disclaimer This content is for informational and educational purposes only and is not a commitment to lend. Appraisal timing, appraisal results, property eligibility, repair conditions, underwriting approval, loan approval, program availability, rates, APR, fees, terms, payment estimates, closing timelines, and closing dates depend on borrower qualifications, property details, appraisal findings, lender guidelines, title review, insurance, underwriting, investor requirements, and applicable program rules. Not all applicants will qualify. Terms may change without notice.
Loan Factory is not affiliated with or acting on behalf of any government agency. FHA, VA, USDA, Conventional, Jumbo, and other loan programs are offered through participating lender partners, subject to eligibility and underwriting approval.
Equal Housing Opportunity.
FAQ: Appraisal to Closing Timeline